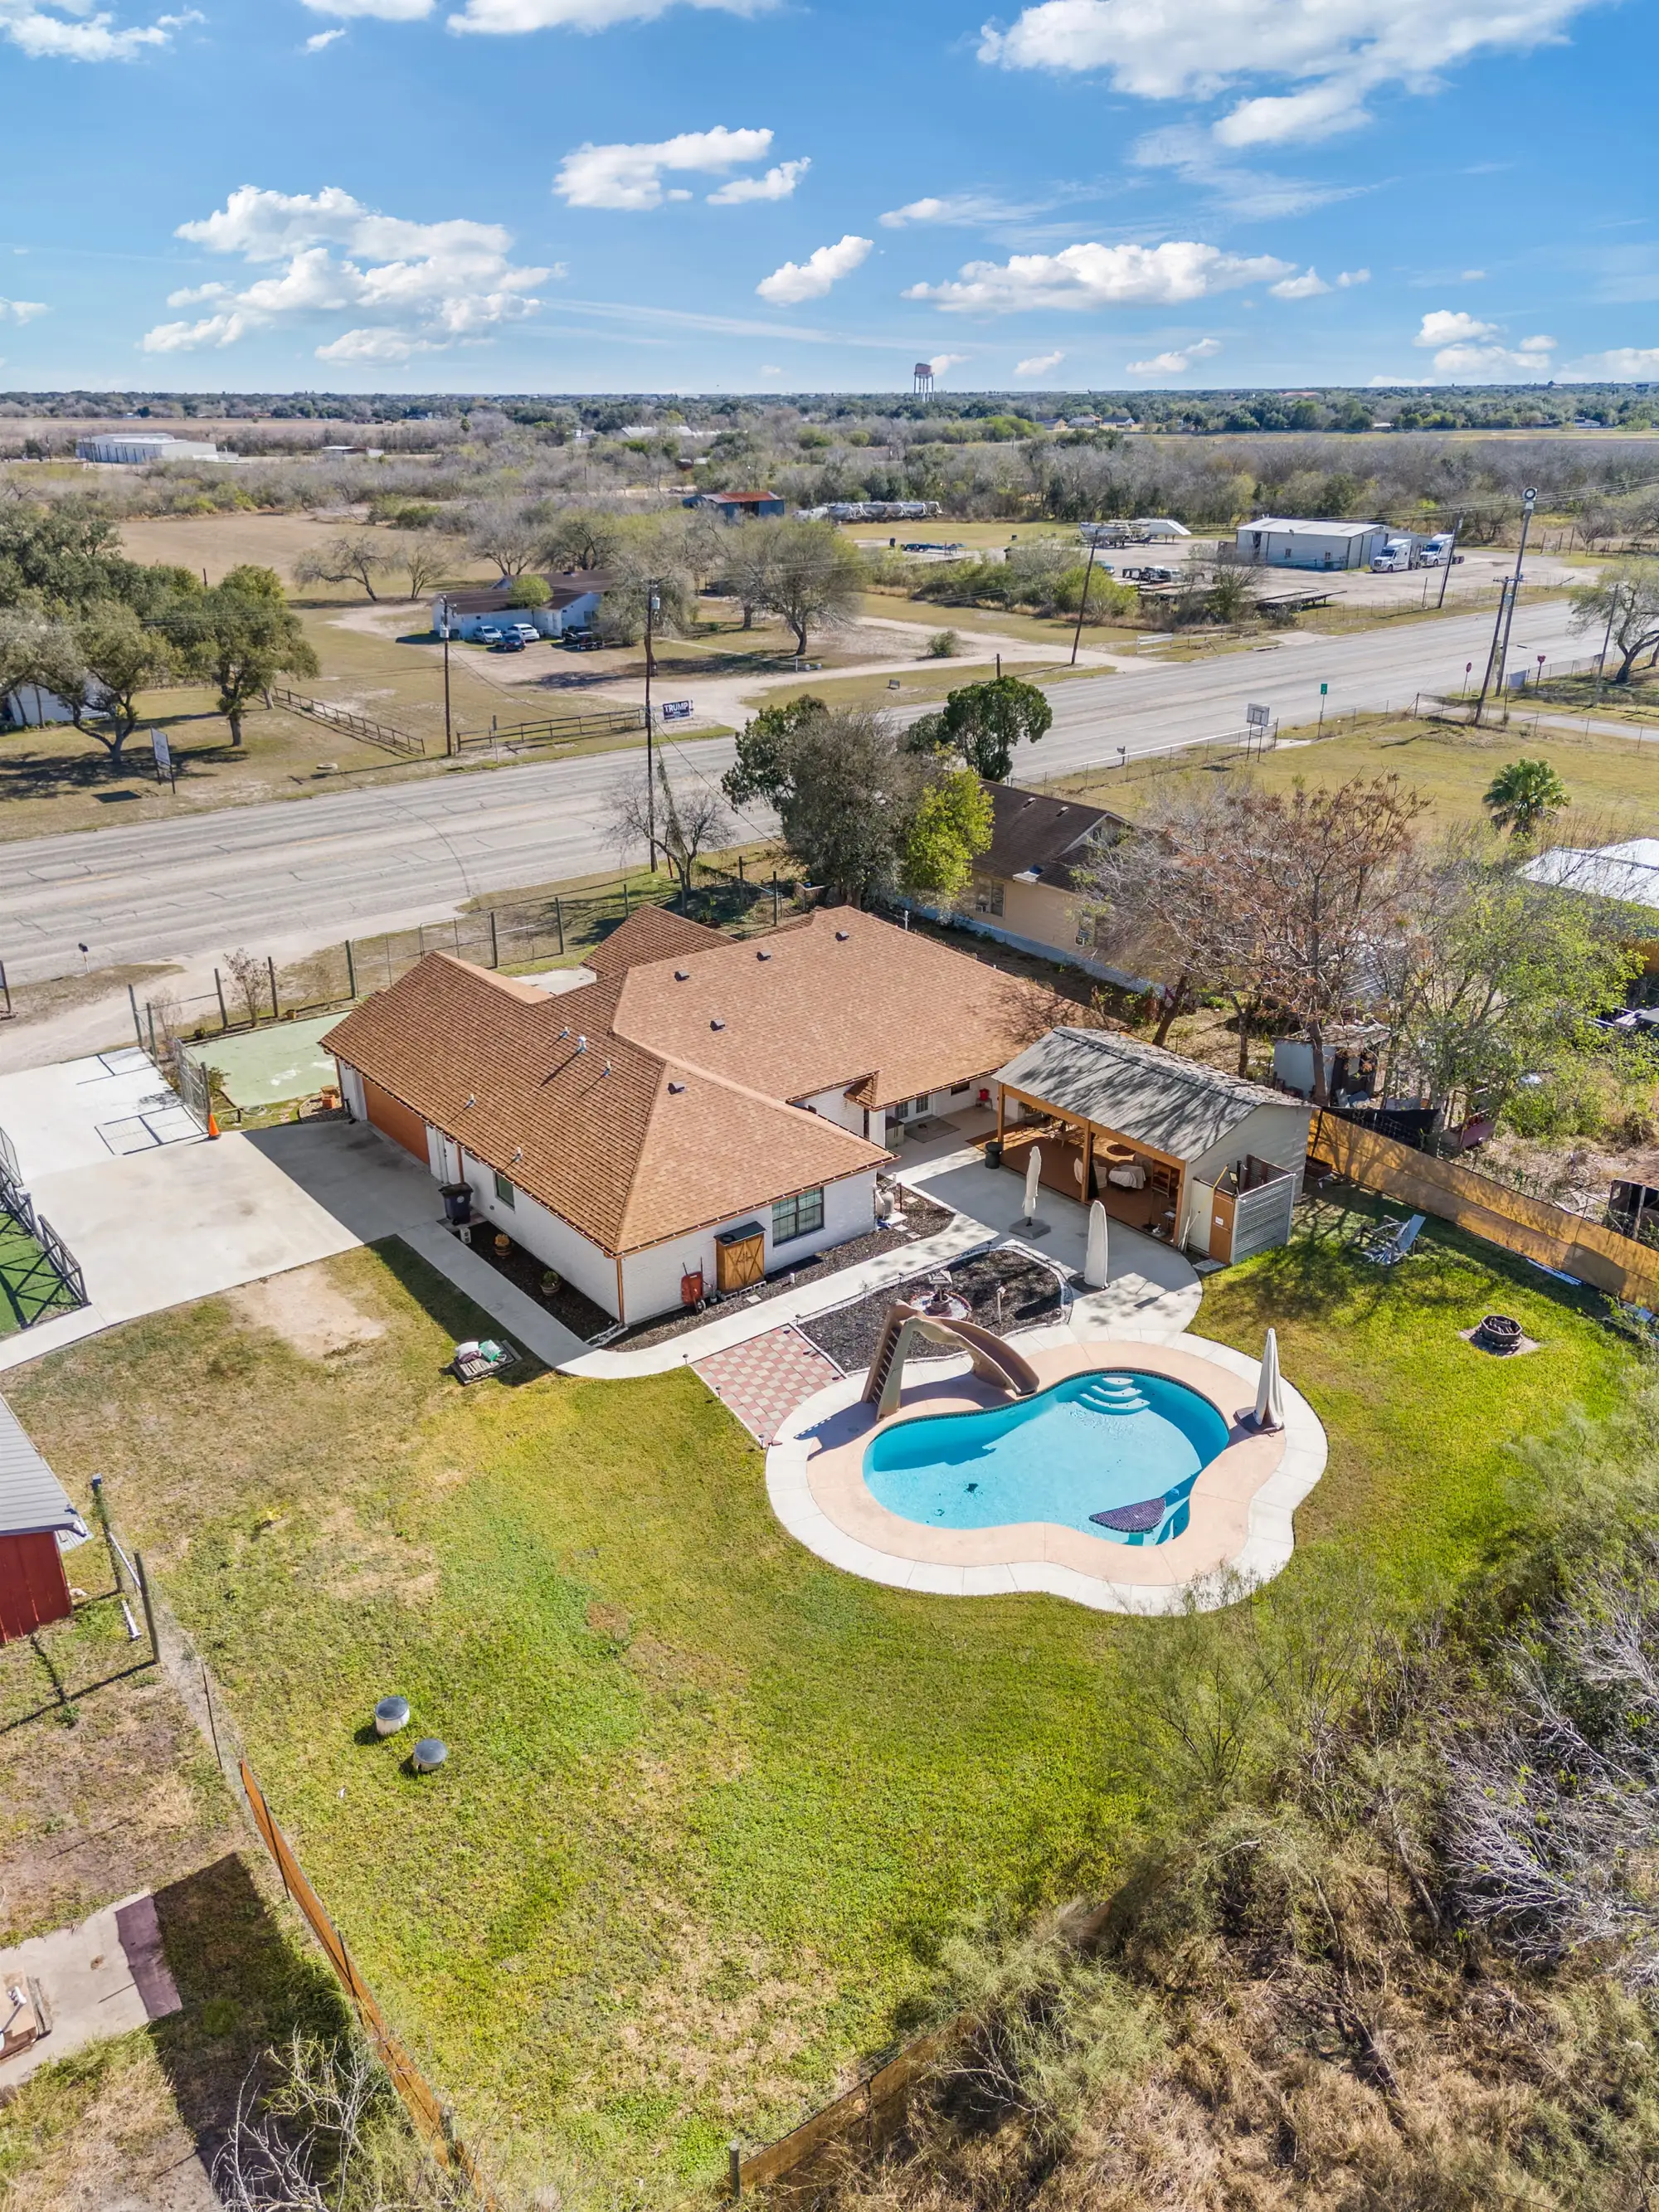
For sale
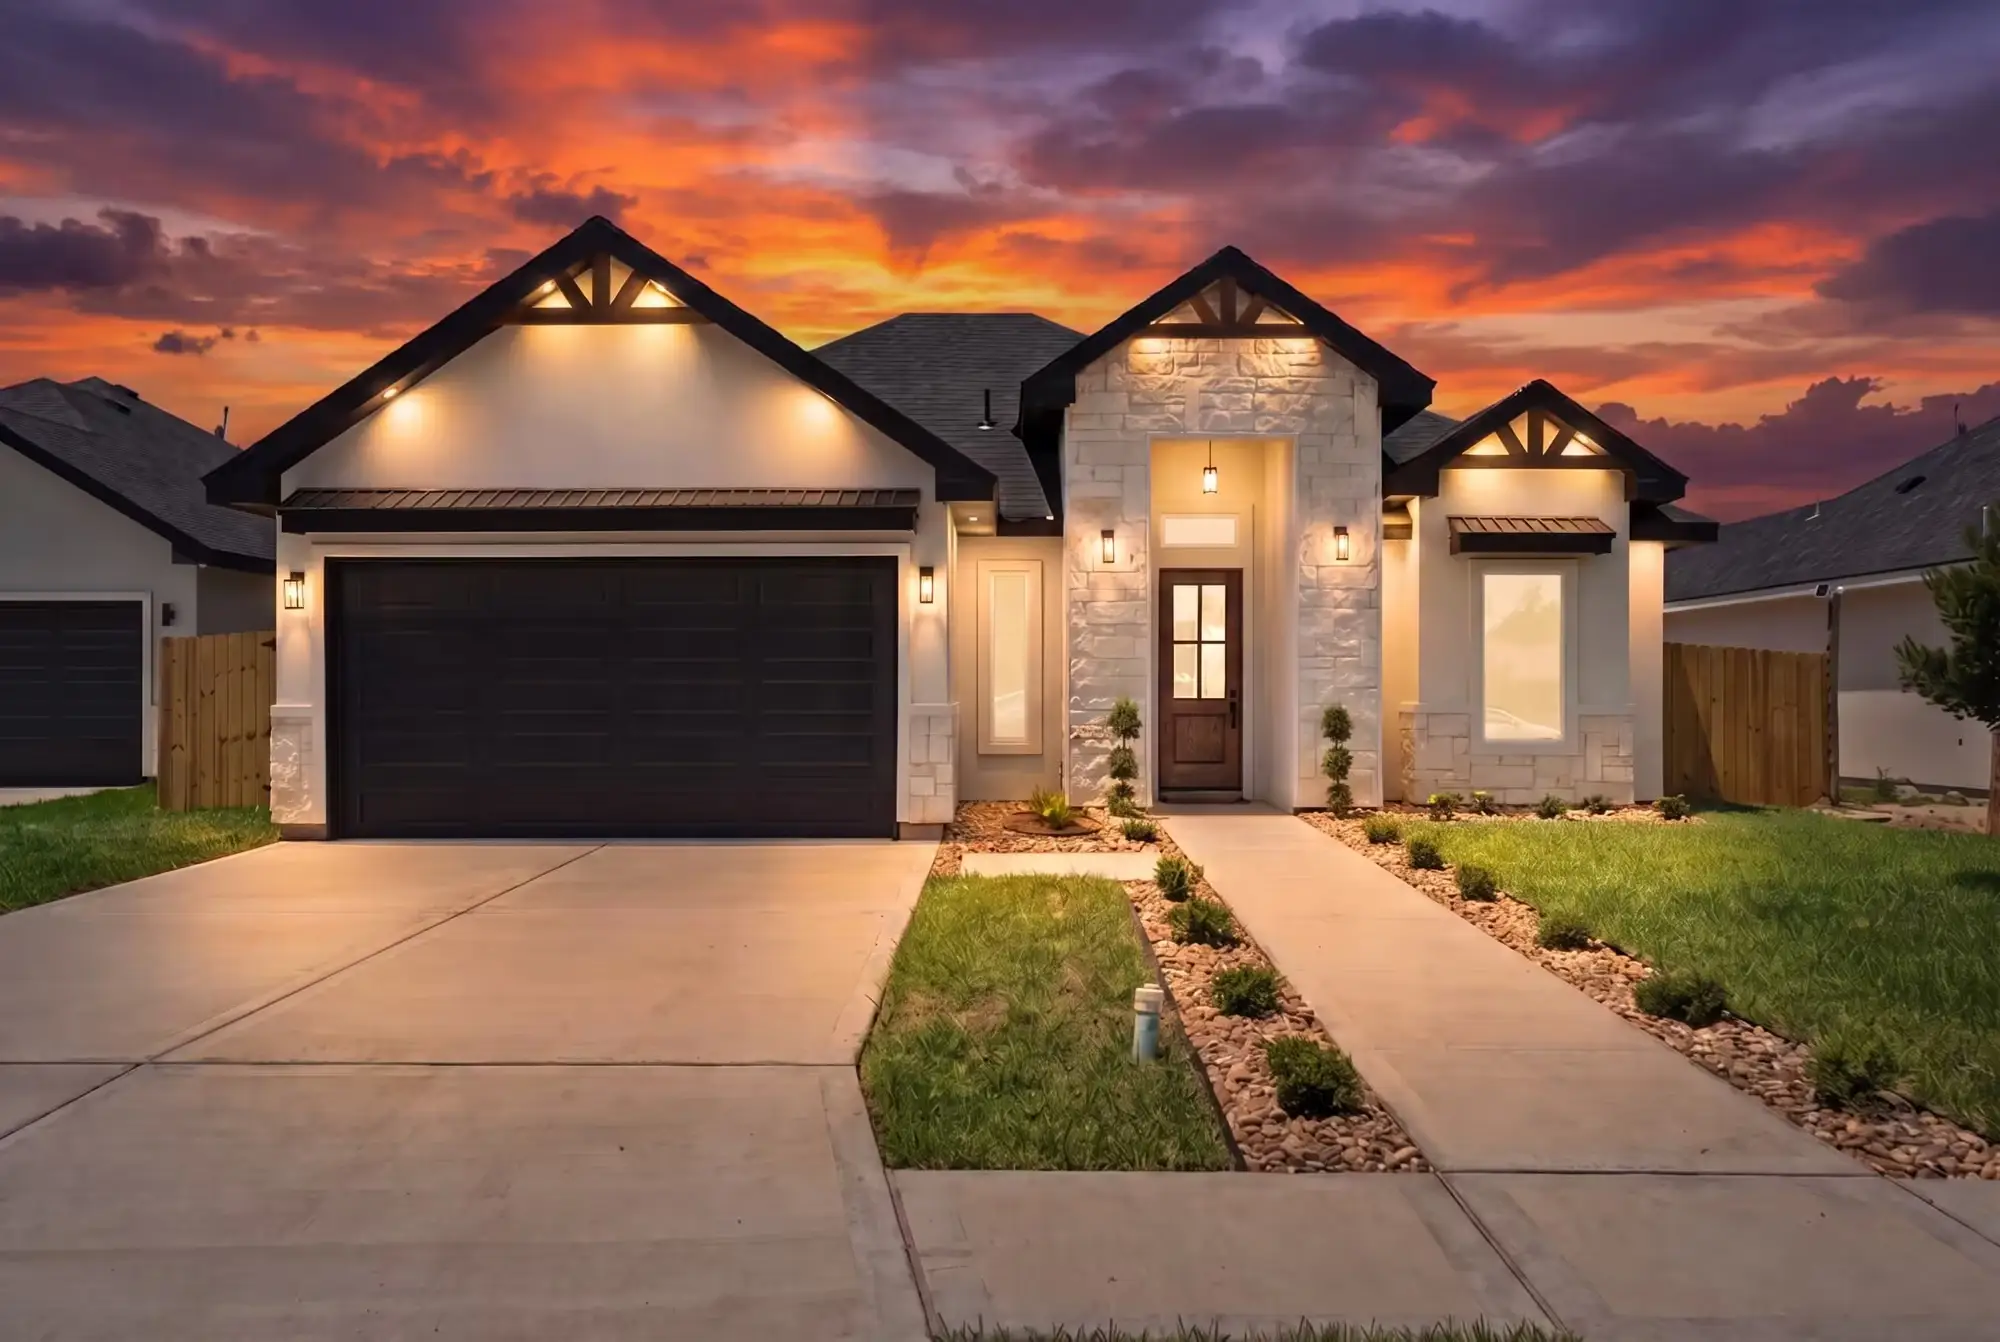
Laguna Oaks, move in ready home
$310,000
Service · Financing
FHA, VA, USDA, conventional and one time close construction loans, explained before you talk to a lender.
We do not lend money. What we do is make sure you walk into a lender knowing which program fits you. For a South Texas build that usually means an FHA construction to permanent loan at 3.5% down, a VA loan at zero down for those who qualify, a USDA loan at zero down in rural areas, or a conventional loan at 10 to 20% down. We introduce you to local lenders who actually close construction loans in the Valley.
Four stages. Nothing is skipped and nothing happens out of order.
stage 01
Five programs, different down payments, different credit floors, different property rules. Twenty minutes here saves months of applying for the wrong thing.
stage 02
Two years of returns, two years of W2s or 1099s, two to three months of bank statements, thirty days of pay stubs, photo ID. VA adds the Certificate of Eligibility.
stage 03
One to three business days with a local lender, at no cost. You come out with a real number, which is what lets us design to a budget instead of a guess.
stage 04
After closing, the lender releases funds in stages as milestones pass inspection. During construction you typically pay interest only on what has been drawn.
Which one fits depends on your down payment, your credit, whether you have served, and whether your parcel qualifies as rural. We will tell you honestly which ones you are a candidate for.
Most popular
One loan covers both the build and the final mortgage. One closing, one set of fees. Available in FHA, VA and conventional versions, and it typically saves $2,000 to $6,000 in closing costs versus closing twice. For most families this is the cleanest path.
Flexible for unusual situations
Short term financing for the build itself. When the house is finished you refinance into a permanent mortgage or arrange one separately. More moving parts, but more flexibility if your situation is likely to change between groundbreak and closing.
Veterans and first time buyers
VA means zero down for eligible veterans, active duty service members and surviving spouses, with no mortgage insurance. FHA means 3.5% down and flexible credit requirements from a 580 score. We work with lenders who actually close these, which matters more than it sounds.
Zero down where eligible
Zero down payment in qualifying rural areas, and a great deal of Starr County and the outer Valley qualifies. Income limits apply. We check eligibility on your specific parcel before anyone gets attached to the idea.
Hands on clients
For clients who want more direct control of the project. We can support the documentation and draw management side while you carry more of the decision making. Fewer lenders offer it, and it is not the right answer for most families.
Program rules, credit thresholds and down payment percentages are set by lenders and federal agencies, not by us, and they change. Nothing here is a commitment to lend or a guarantee of approval.
A construction loan does not hand you a lump sum. The lender releases funds in phases as the house progresses, and each release requires documentation and an inspection. This is the part that goes wrong at other builders.
About 15%
Released once the slab is poured, cured and has passed the municipal foundation inspection.
About 25%
The largest single draw. Structure up, roof on, house dried in, framing inspection passed.
About 20%
All three rough ins installed and inspected while the walls are still open.
About 15%
Spray foam in, drywall hung, taped and floated.
About 15%
Cabinetry, countertops, flooring, fixtures, paint and trim.
About 10%
Released after the final inspection and the certificate of occupancy from your jurisdiction.
Percentages are typical and vary by lender and loan program. Your lender sets your schedule; we build to it.
You never see this part, but it is the difference between a build that funds on time and one that stalls waiting on paperwork.
Submitted complete the first time, with the documentation the lender actually asked for. A rejected draw costs you weeks.
Photographs, inspection reports and invoices that match the phase being claimed. Our transaction coordinator manages this so you are never the messenger.
Scheduled ahead of the phase completing rather than after, so the inspector is not the bottleneck.
If something is going to slip, your lender hears it from us before it becomes a funding problem.
This is the single most underused fact in construction lending, and it is why the Build On Your Lot programme and the financing conversation belong together.
The equity in a parcel you already own can serve as part or all of the required down payment on a construction loan. Families who inherited land, or bought it years ago, routinely discover they need far less cash at closing than they assumed.
The lender appraises the land as part of underwriting. What you paid for it and what it appraises at today are frequently different numbers, usually in your favour if you have held it a while.
Inherited parcels sometimes carry heirship issues that have to be resolved before a lender will accept them. Better to find that out at the start than three weeks before closing.
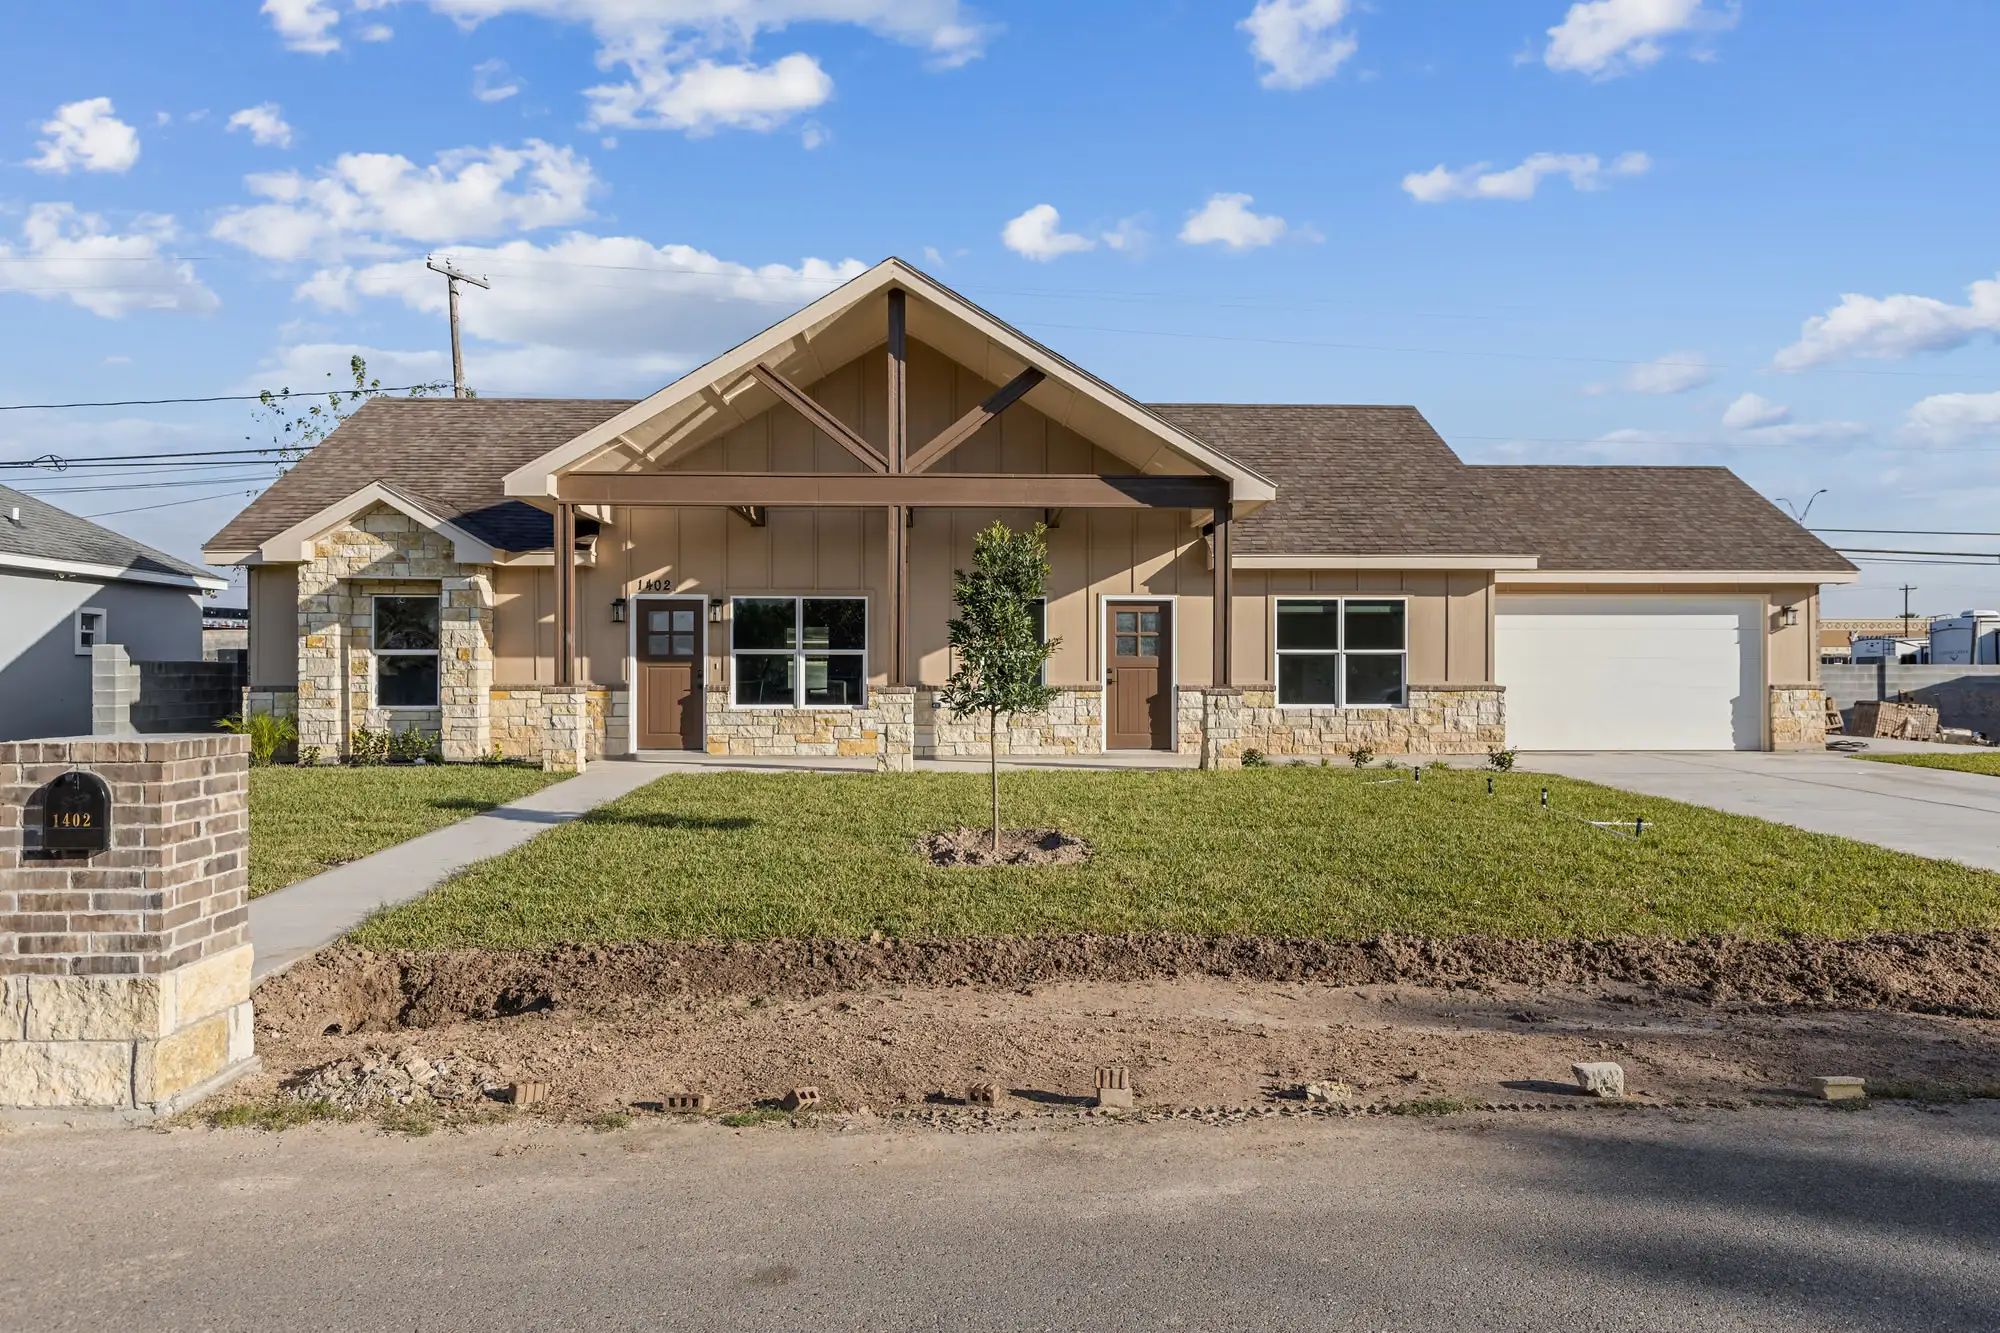
For sale
$310,000
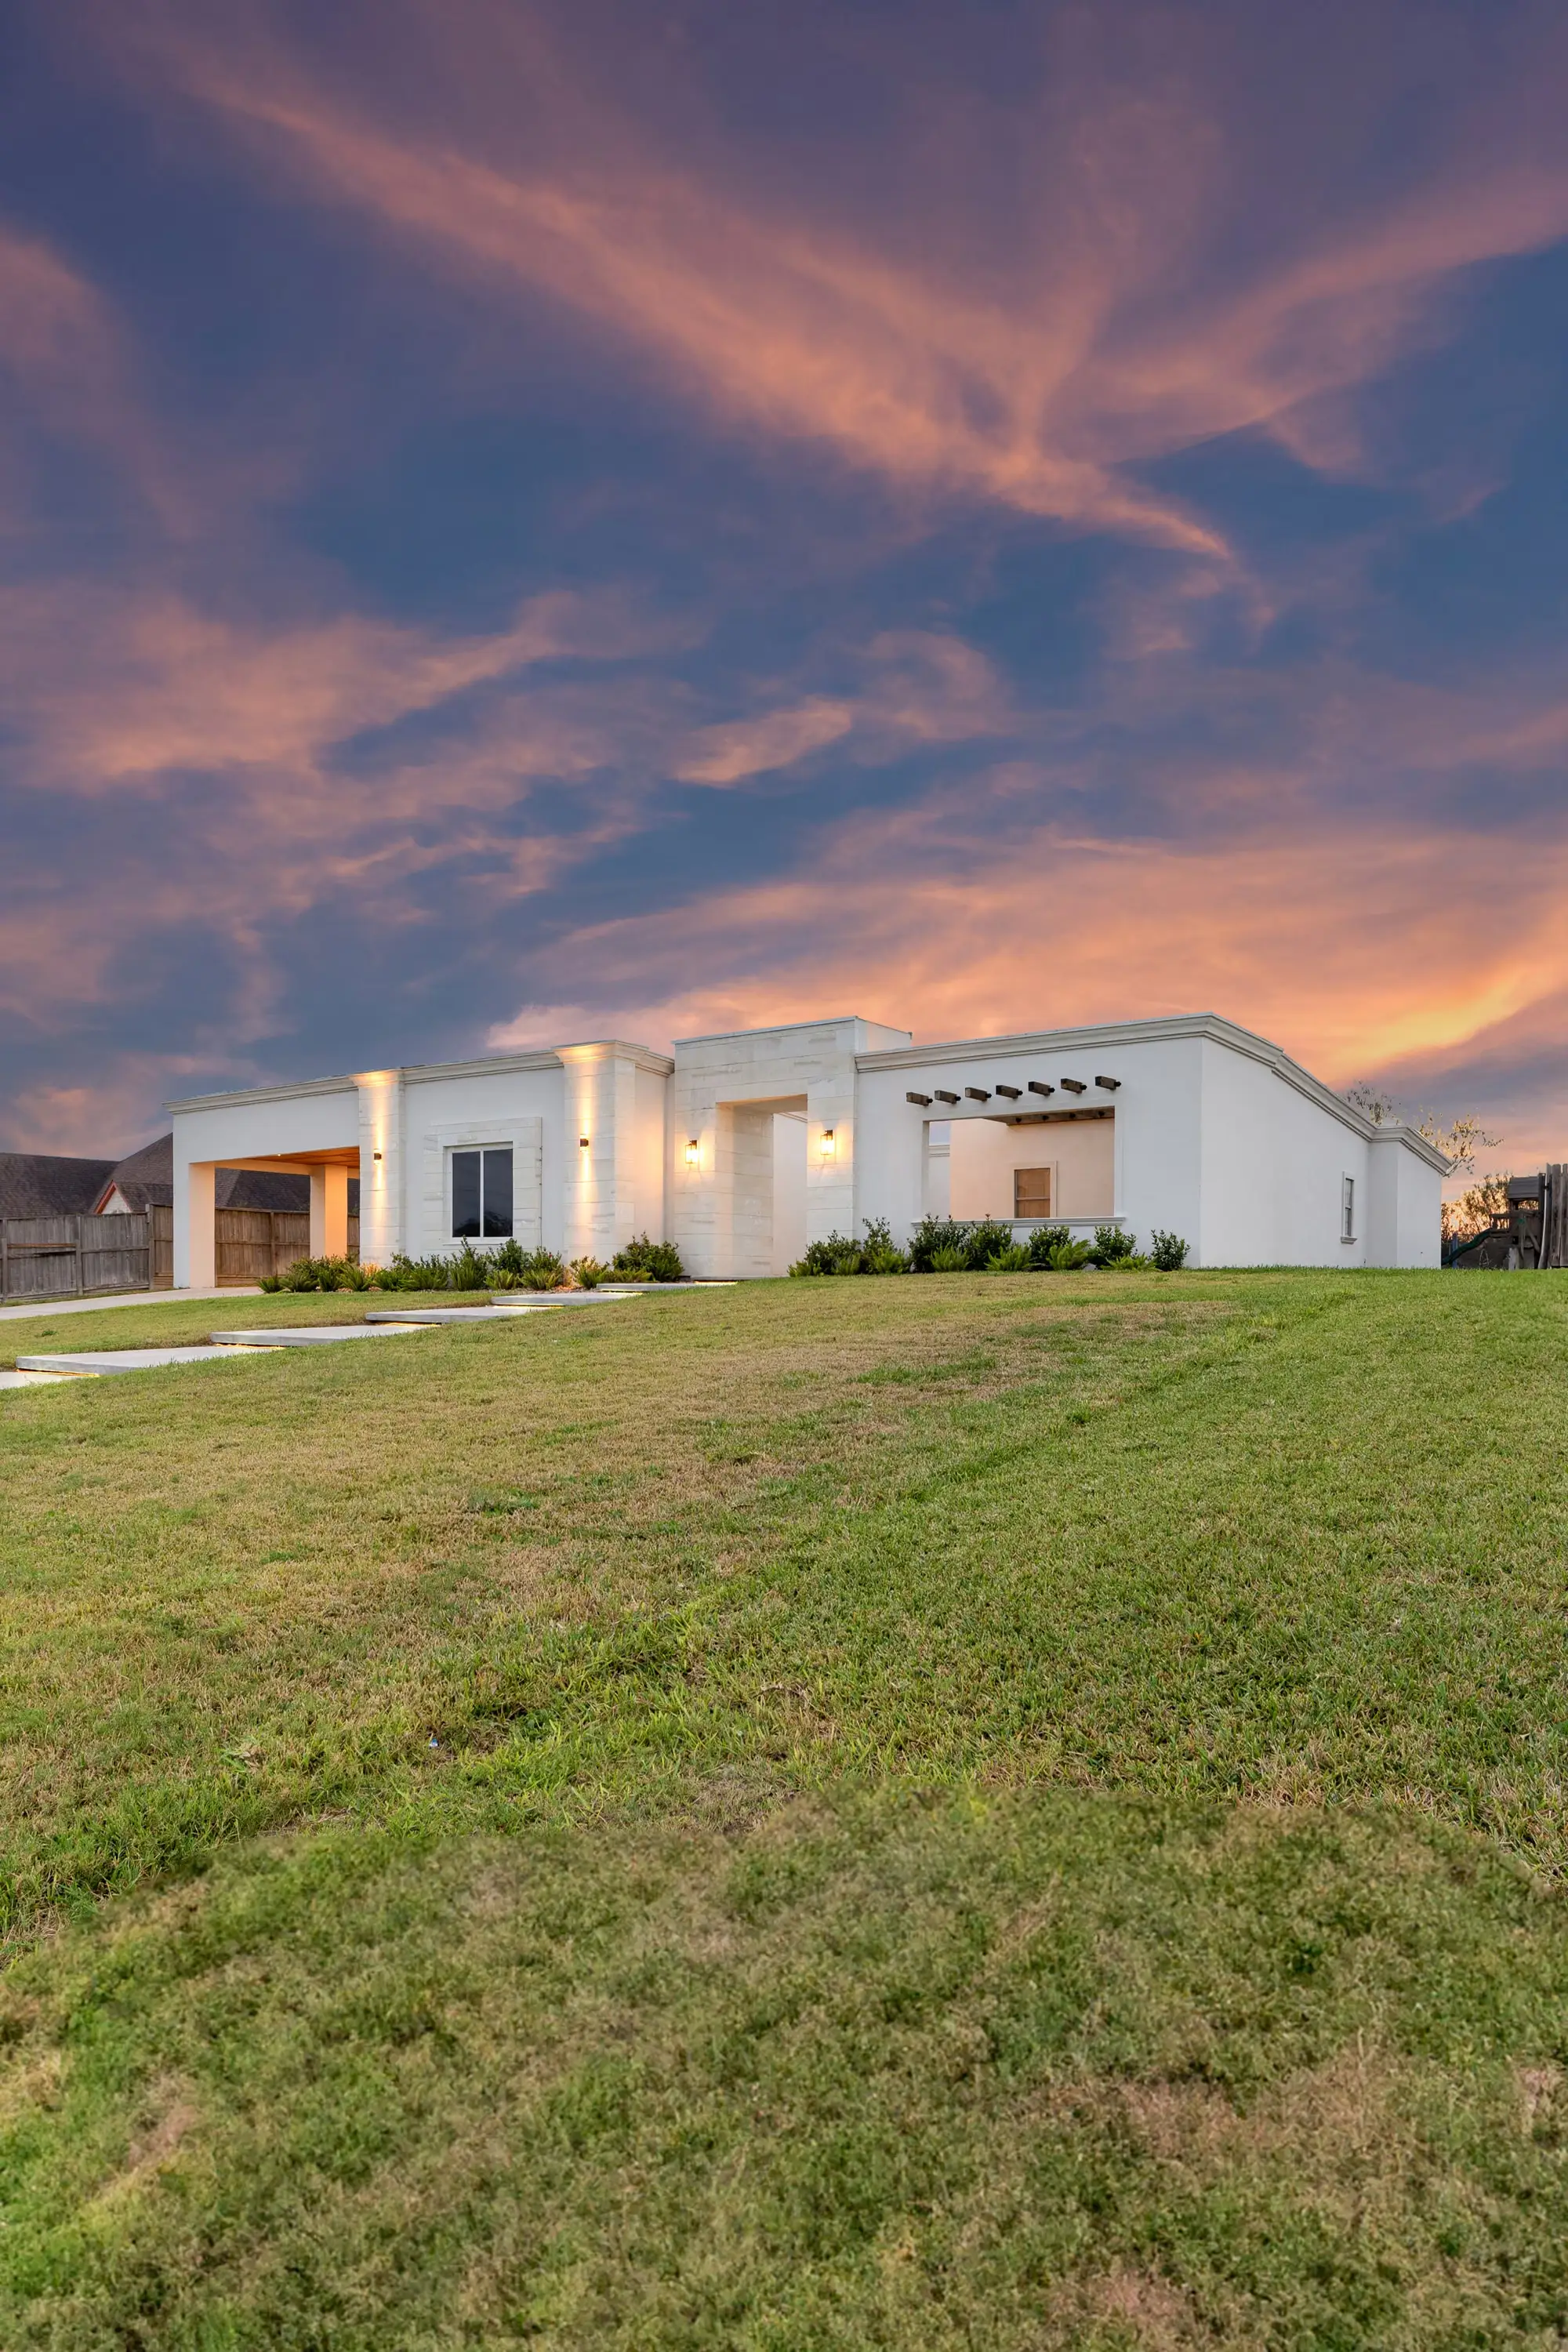
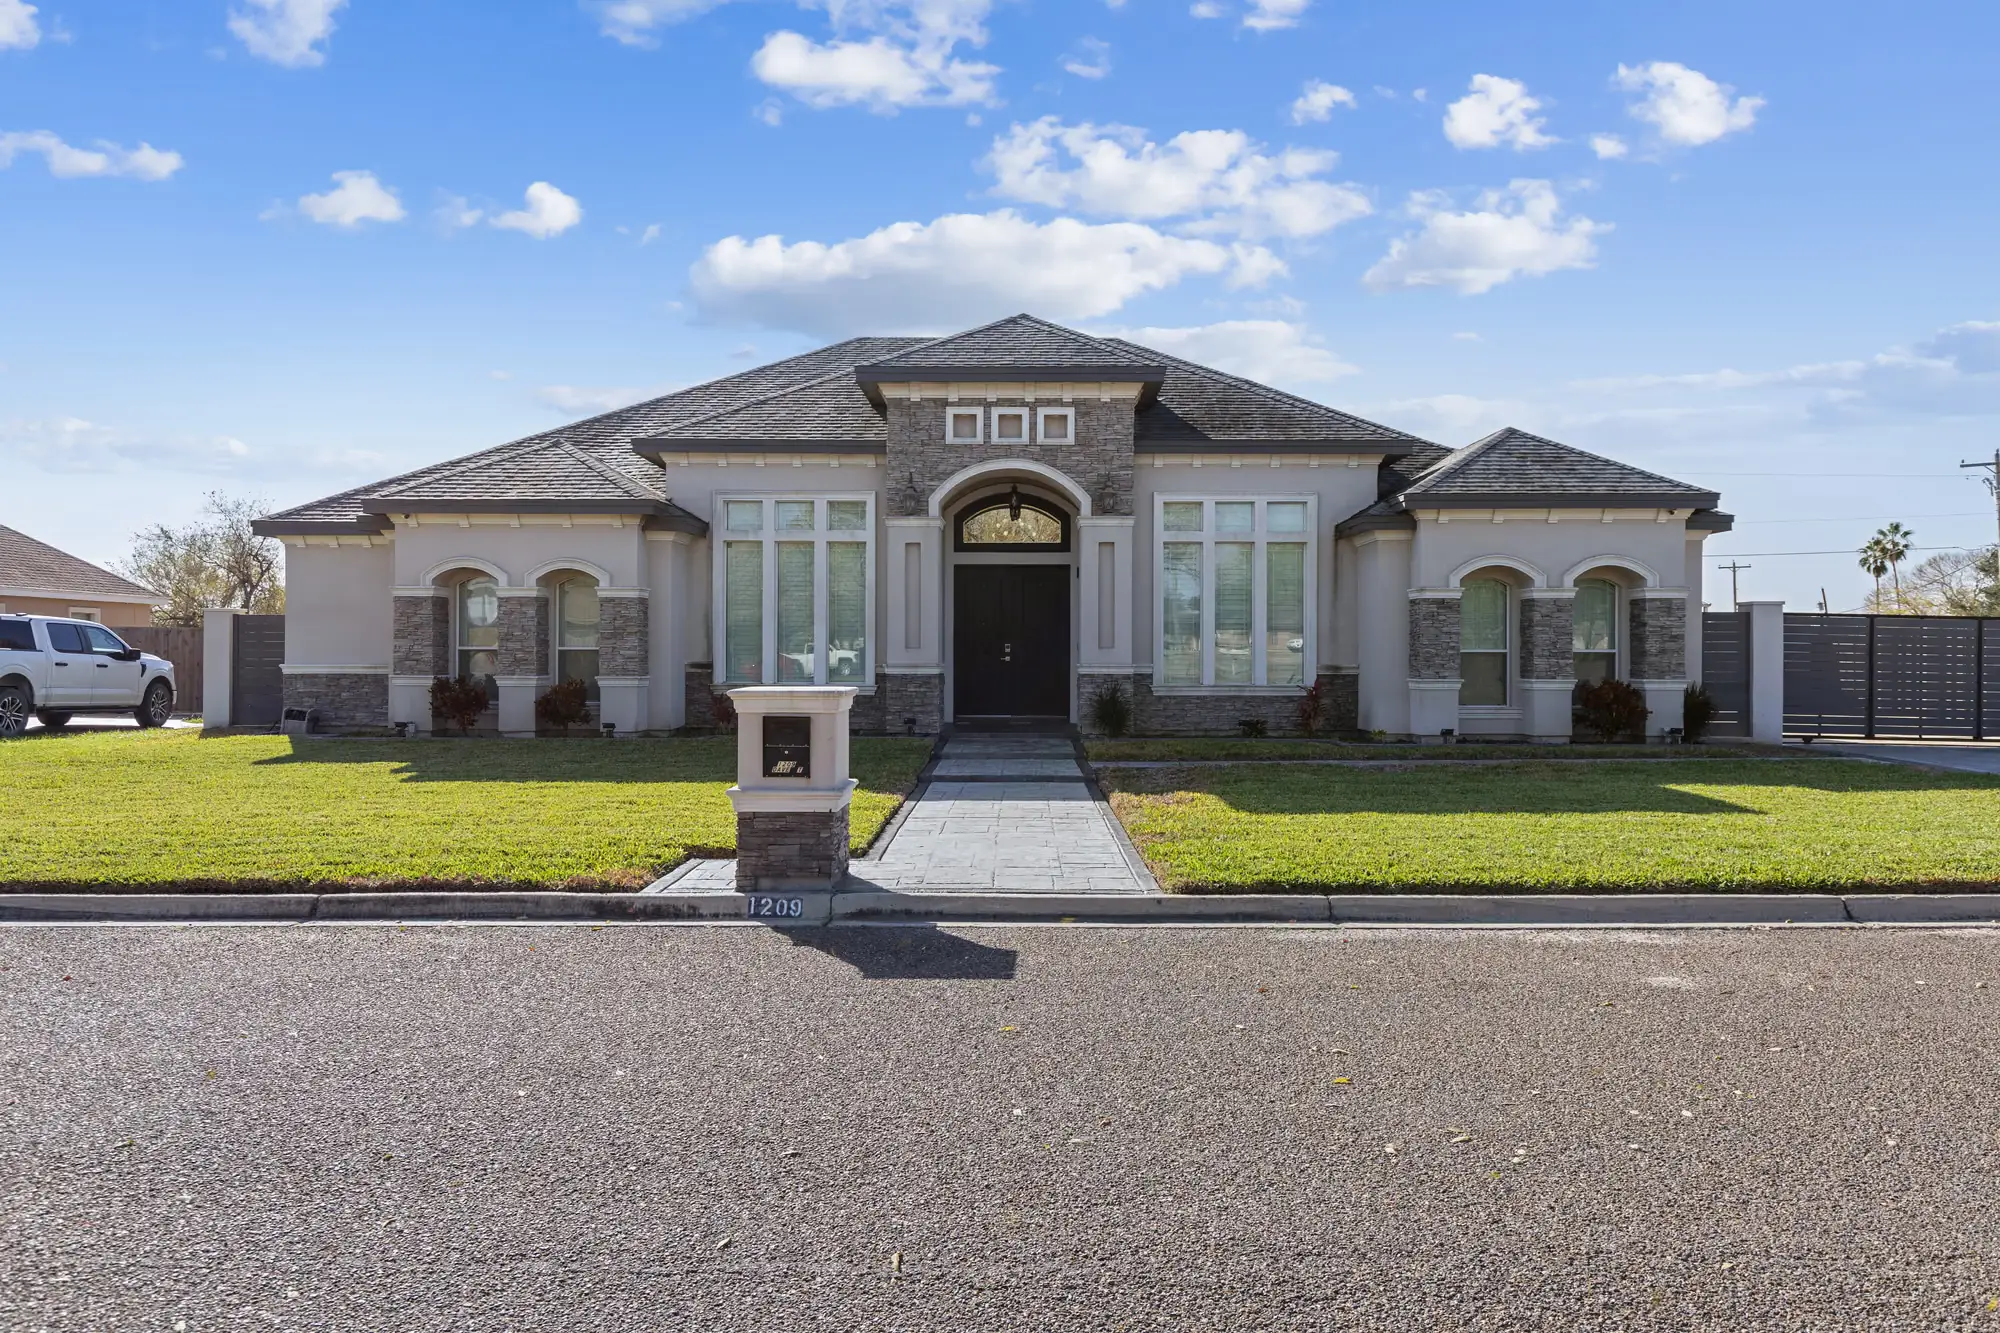
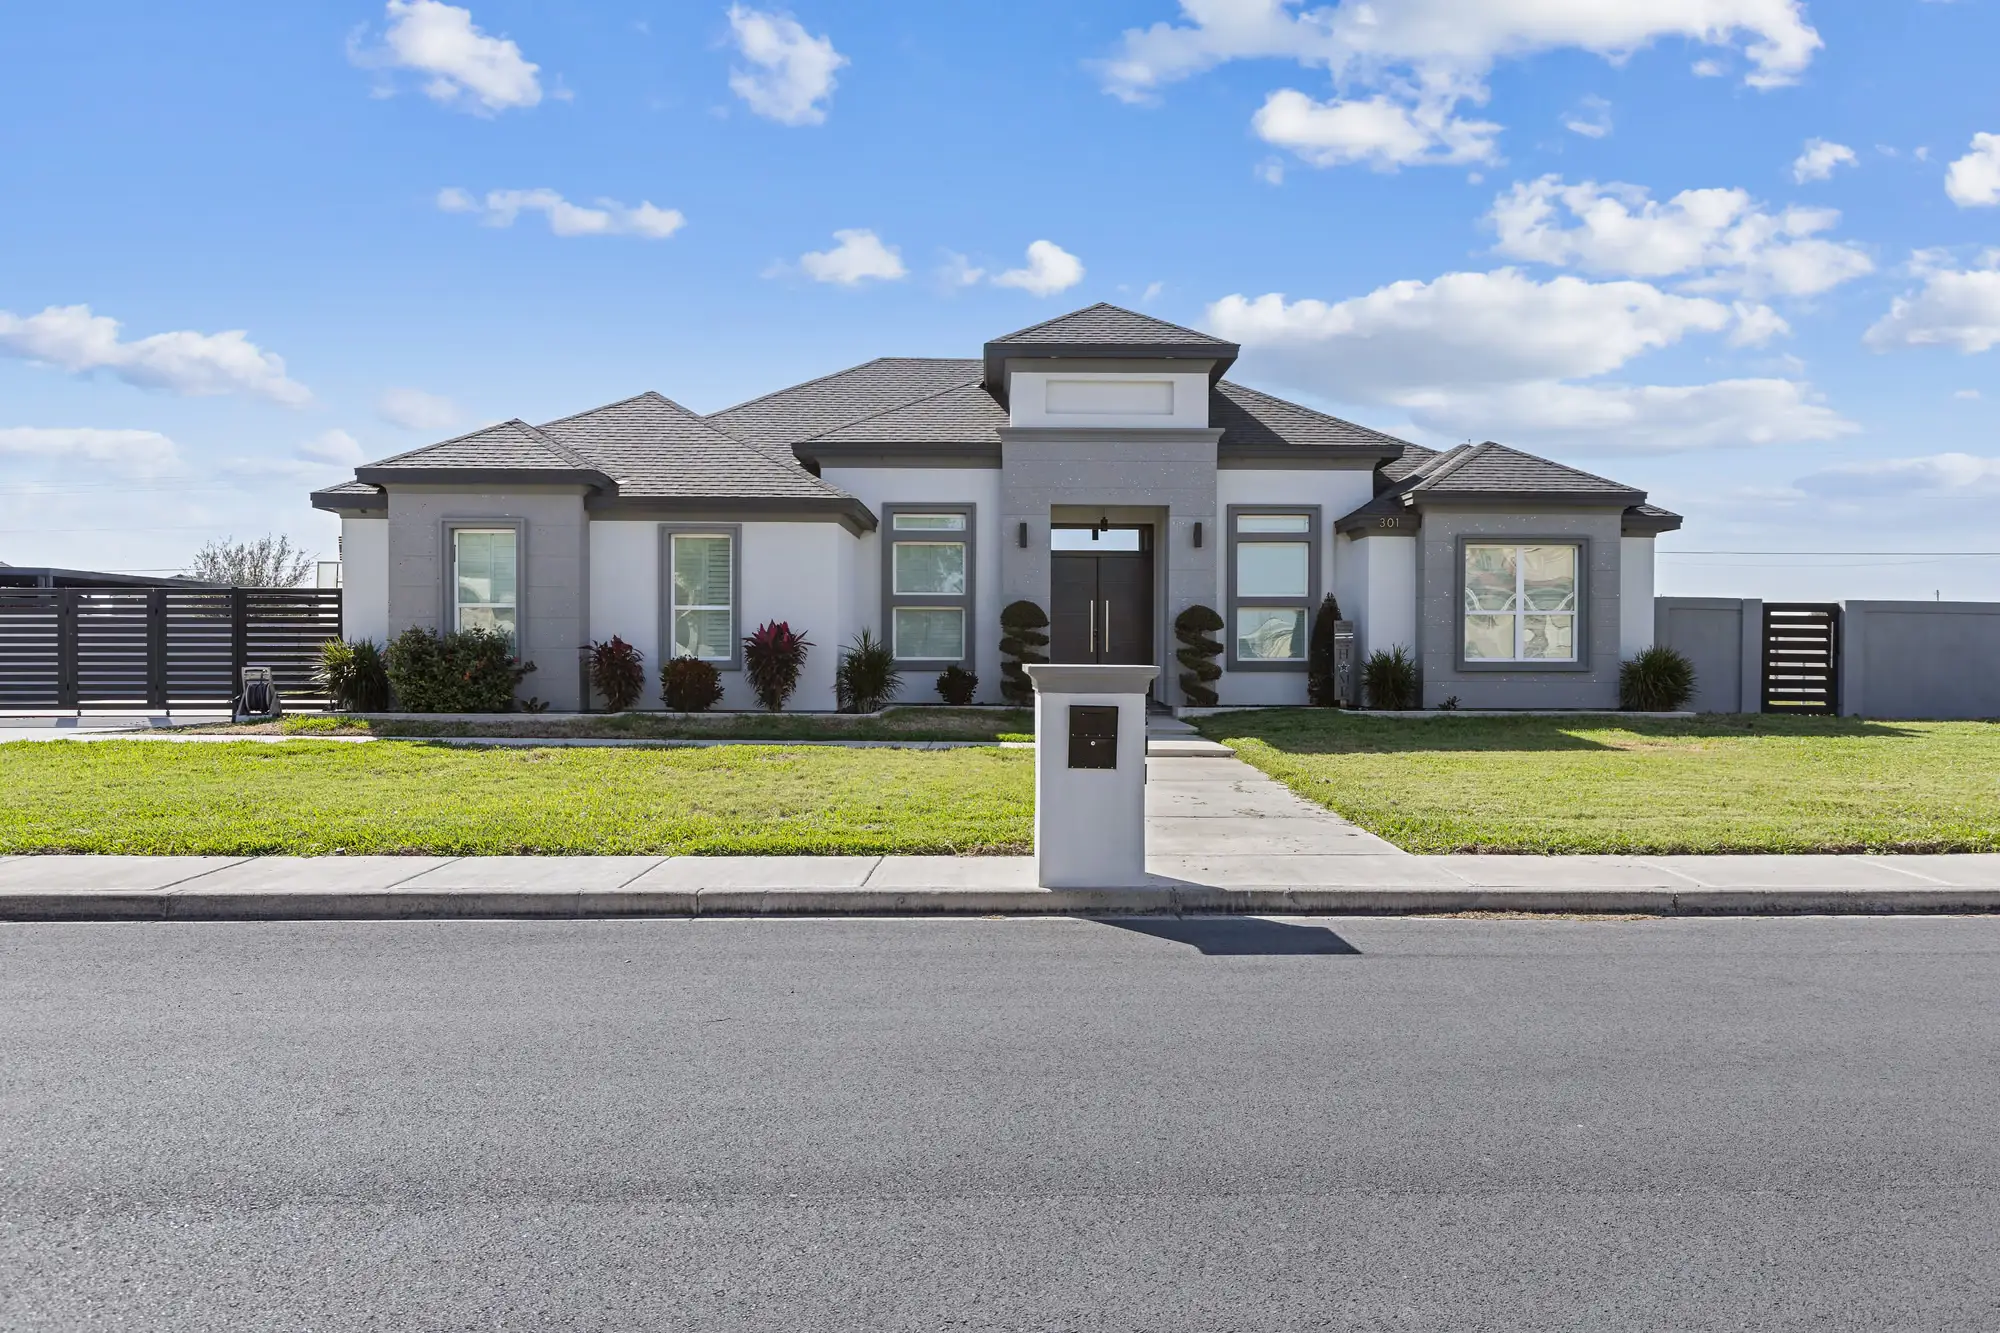
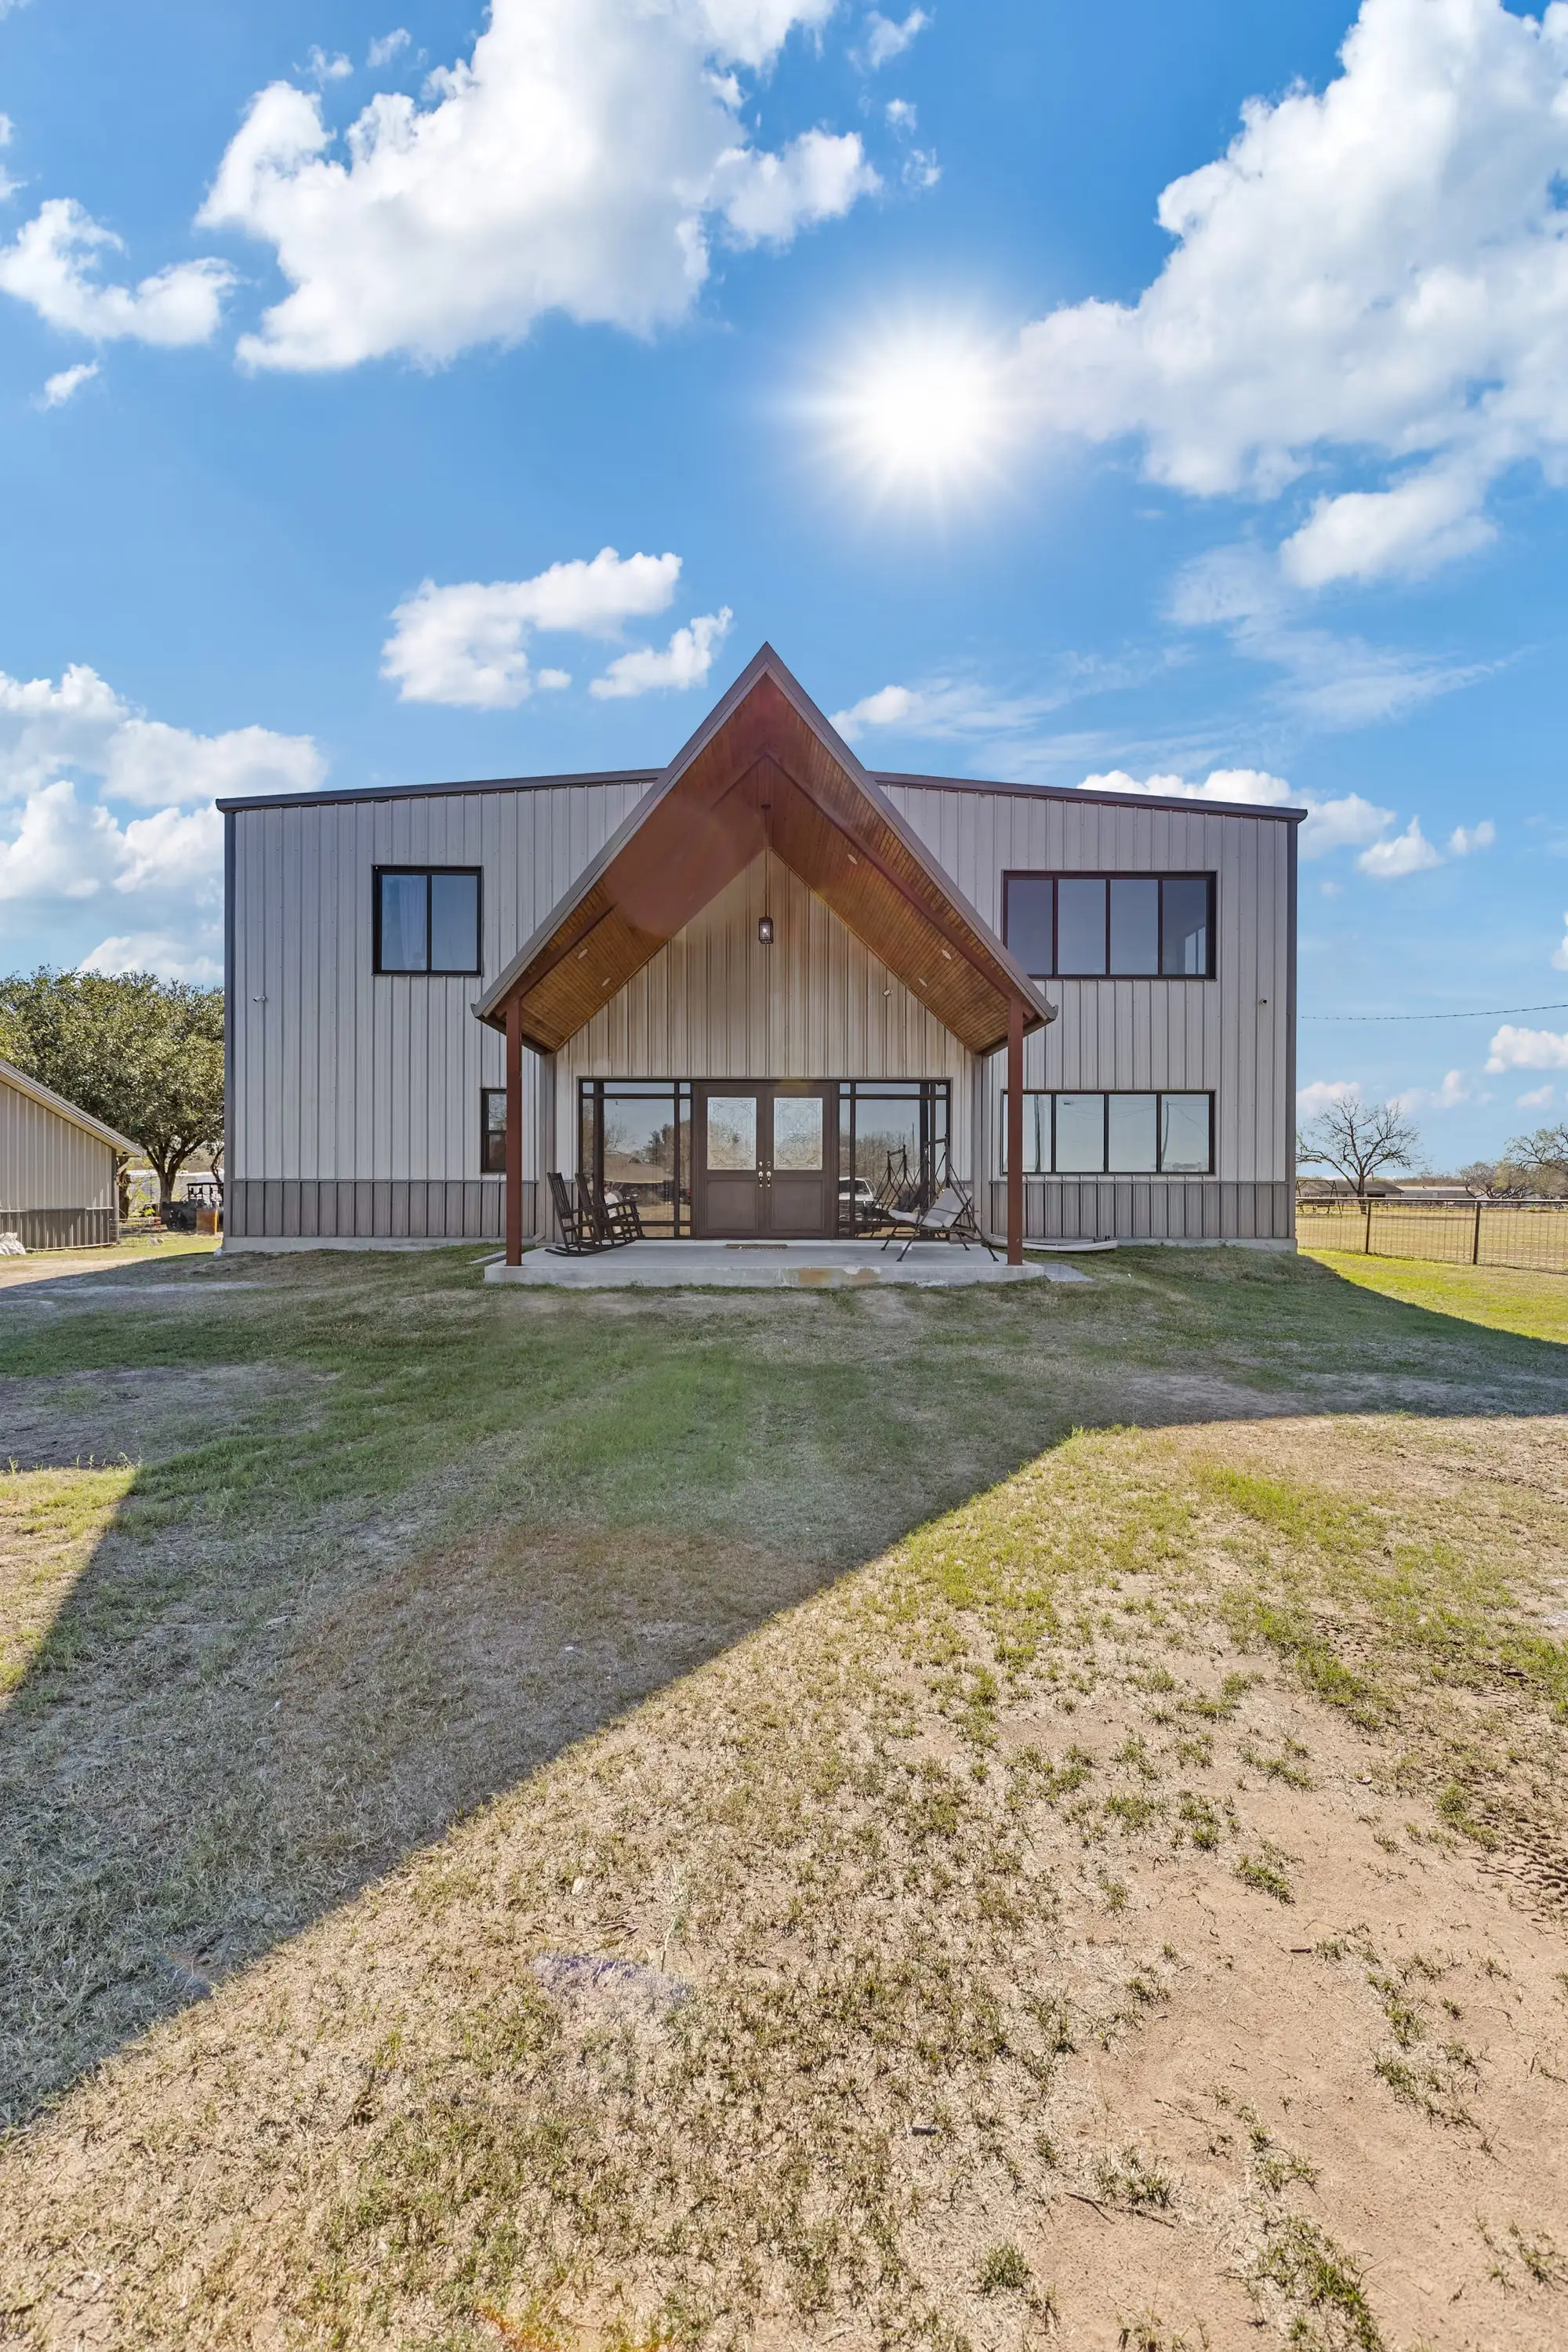
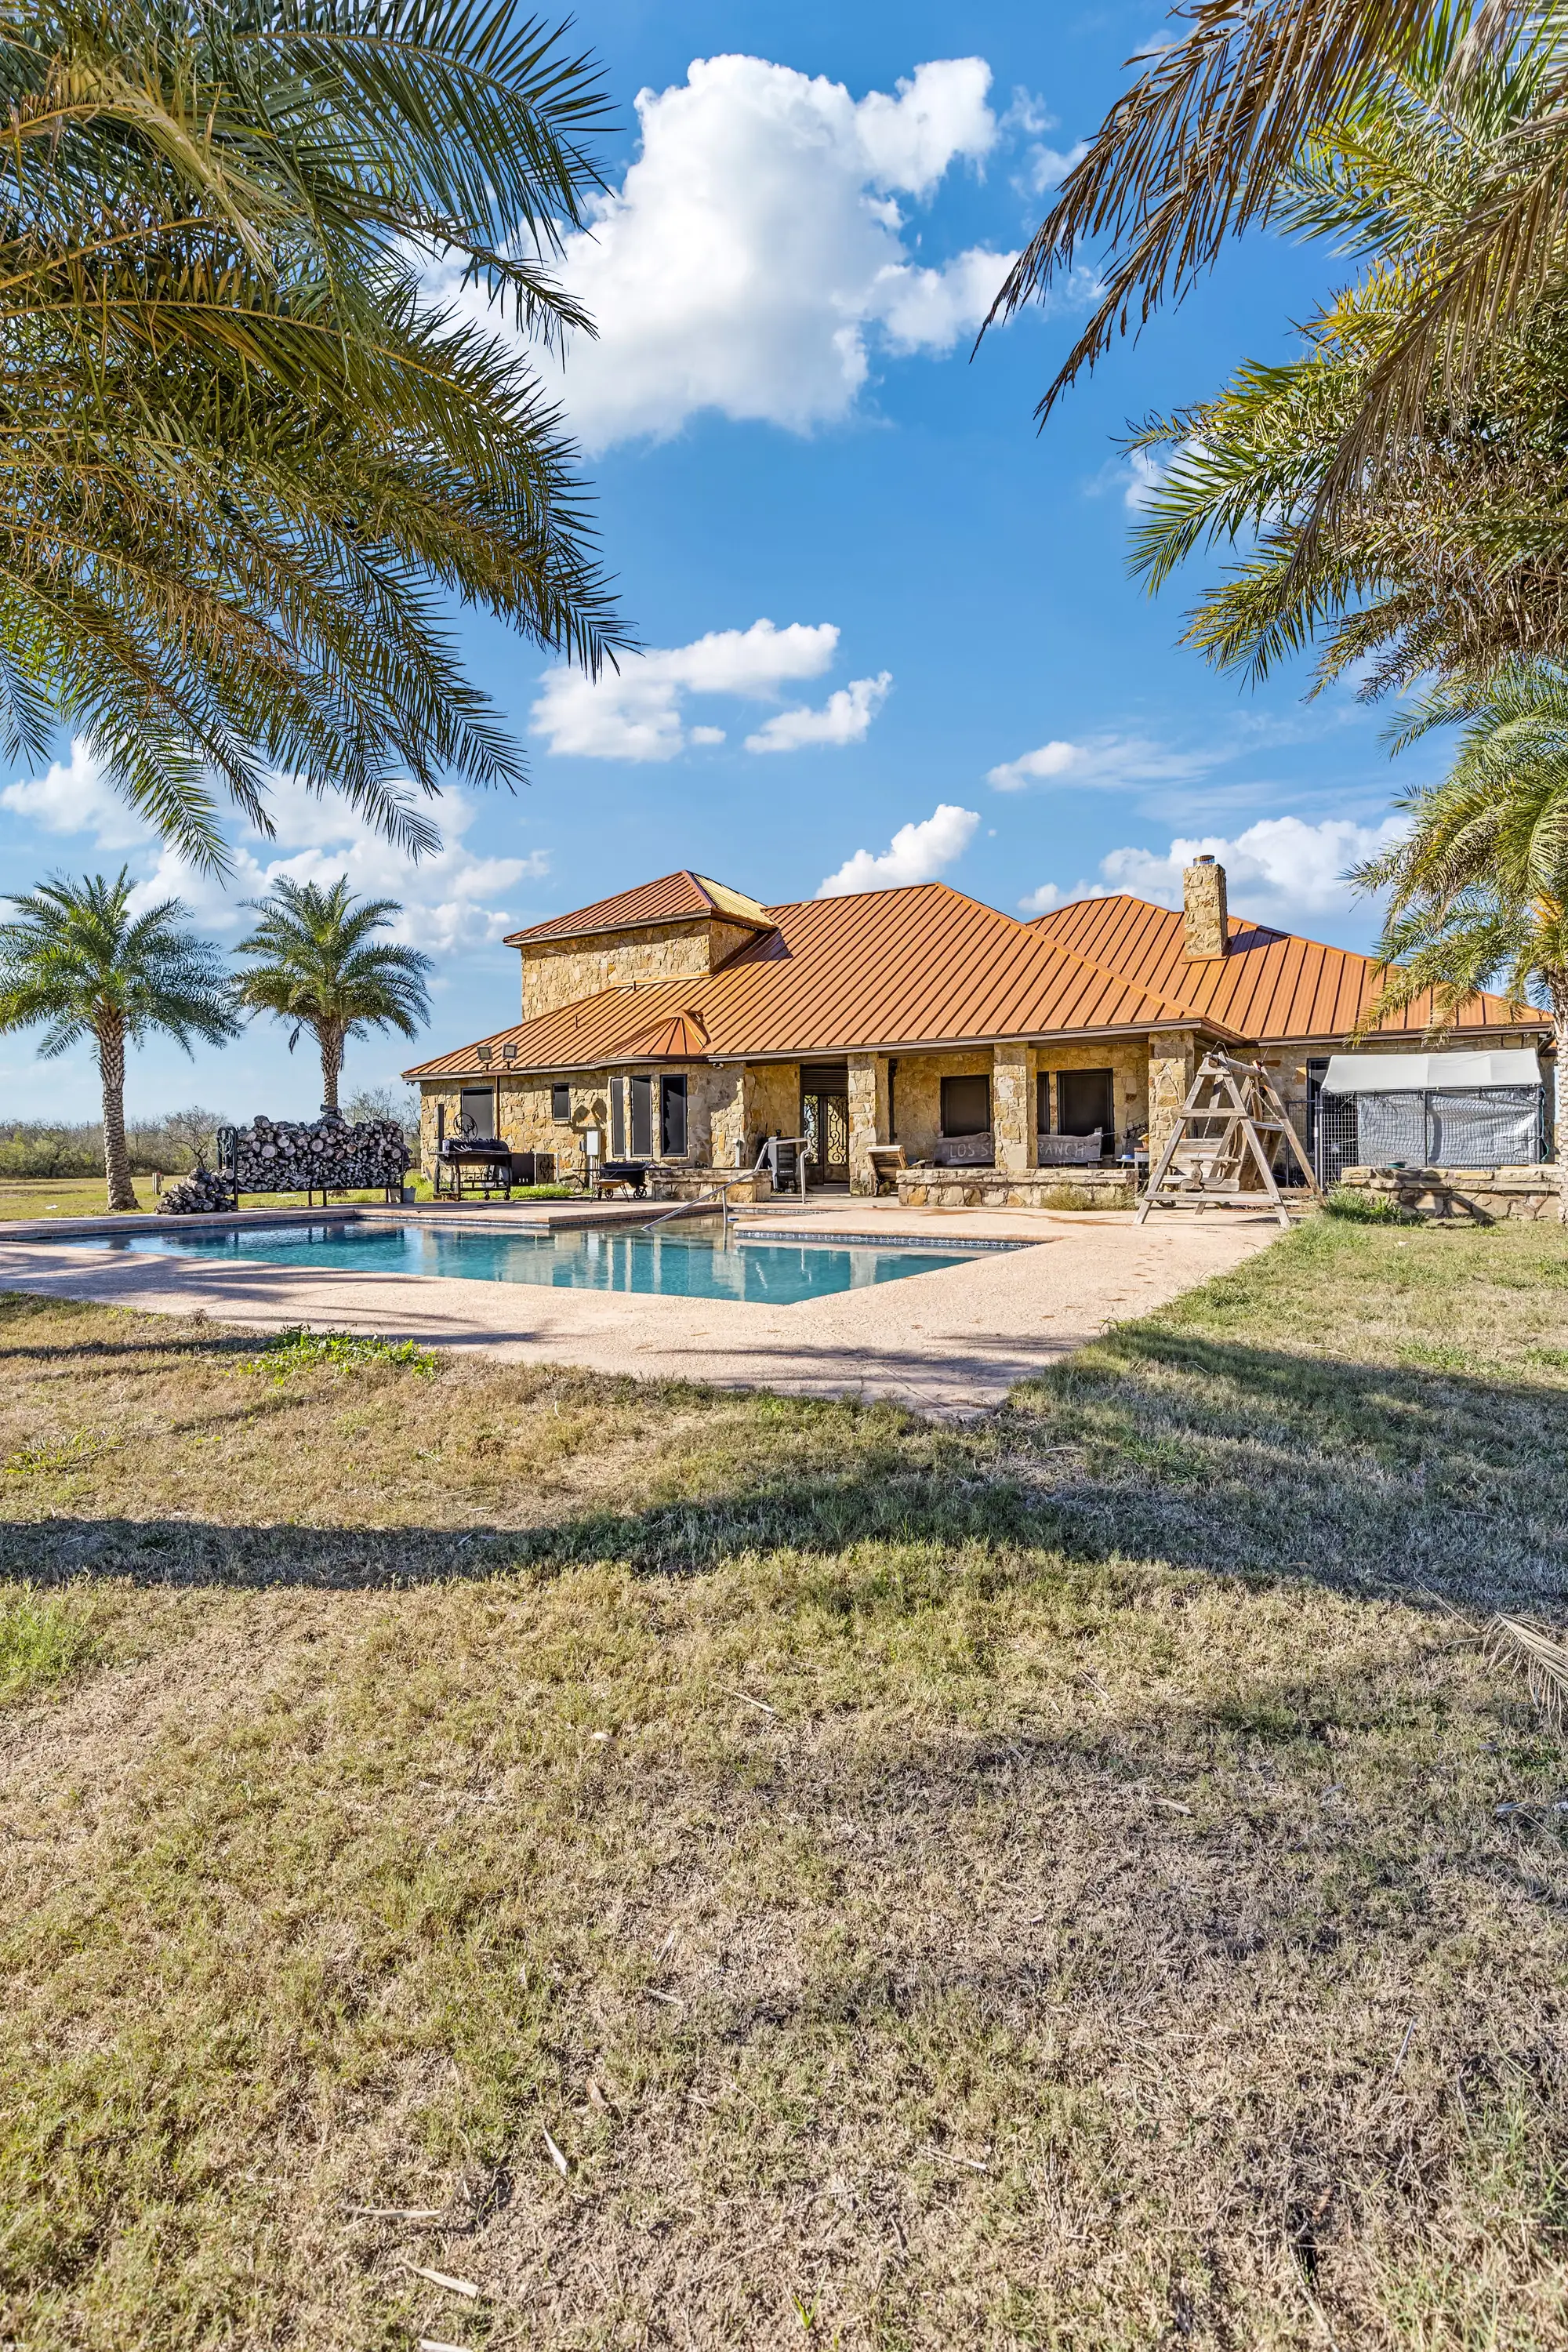
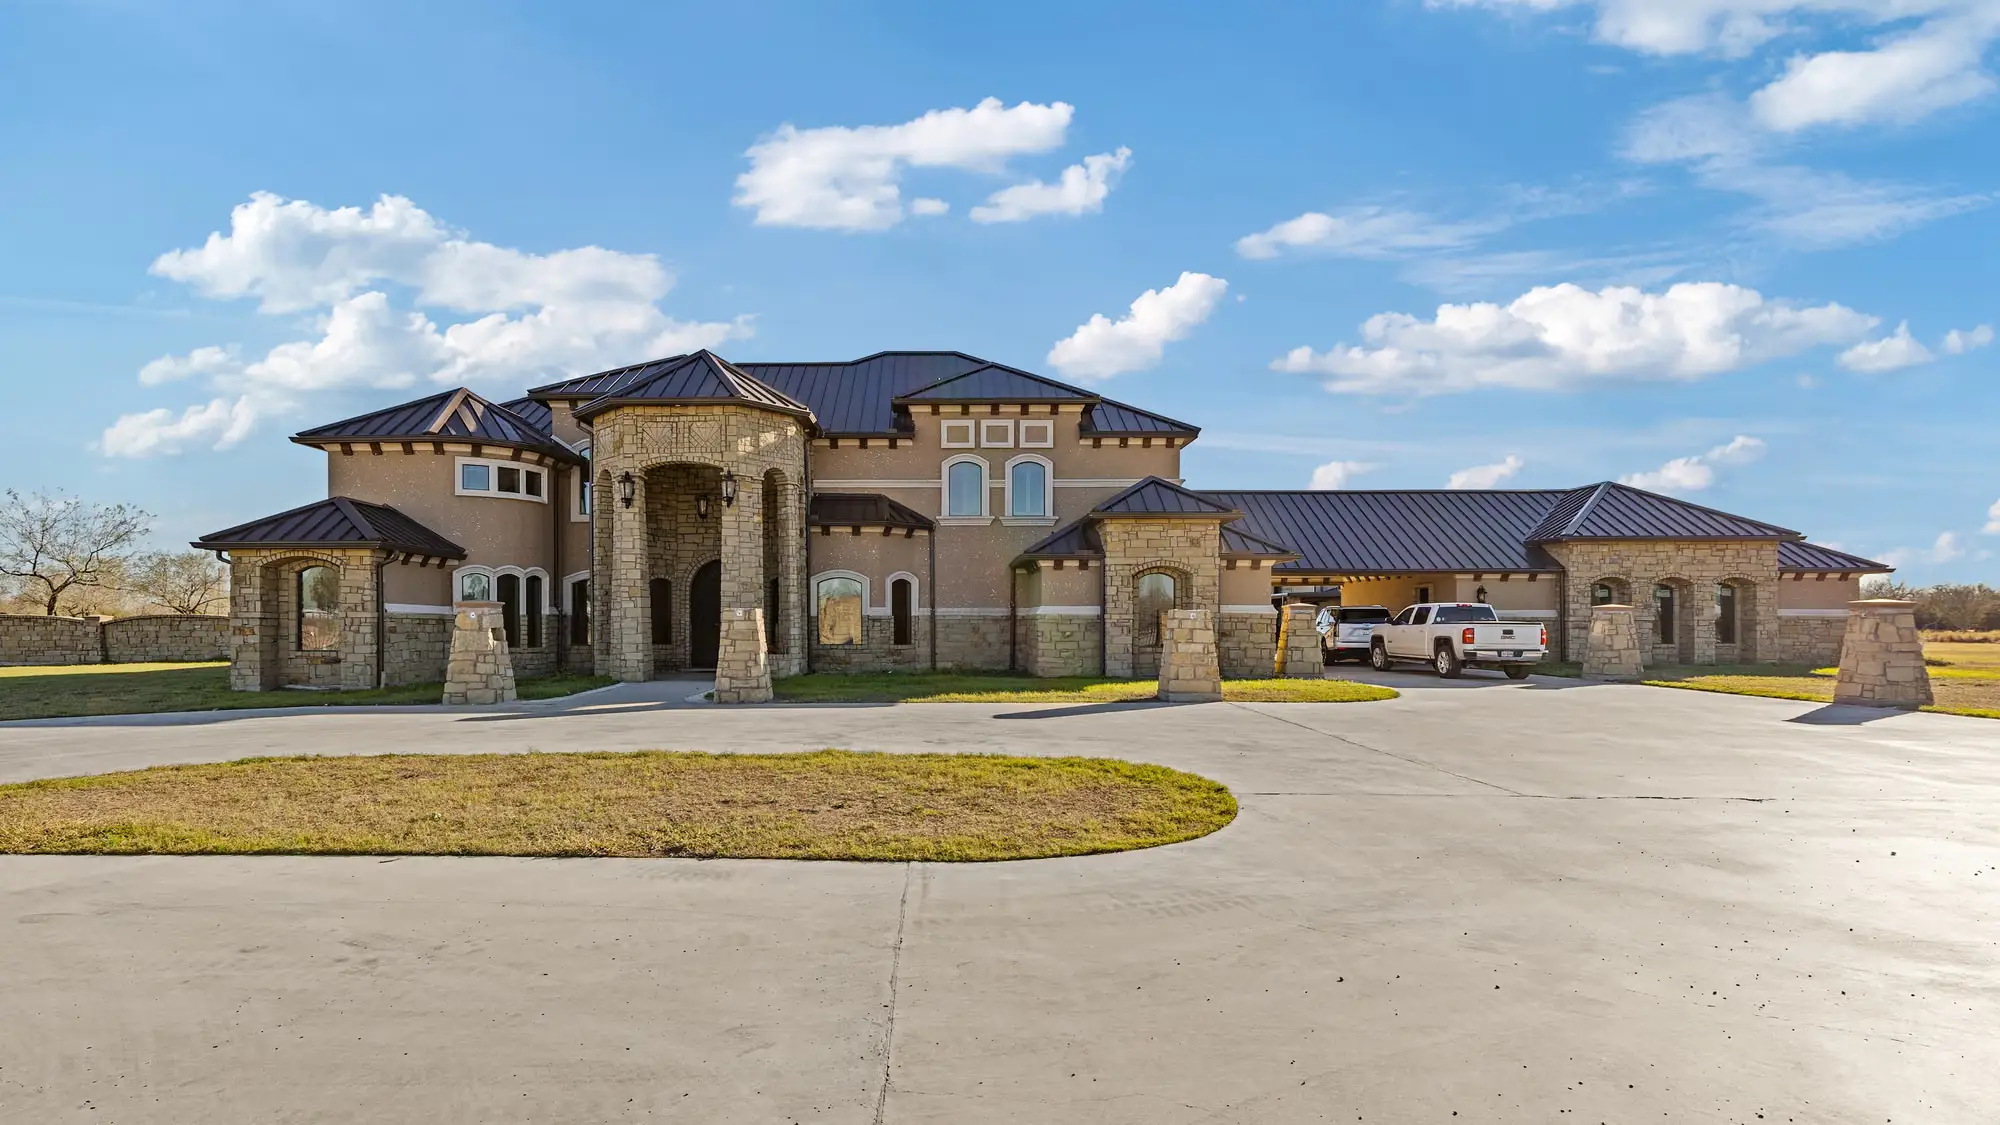
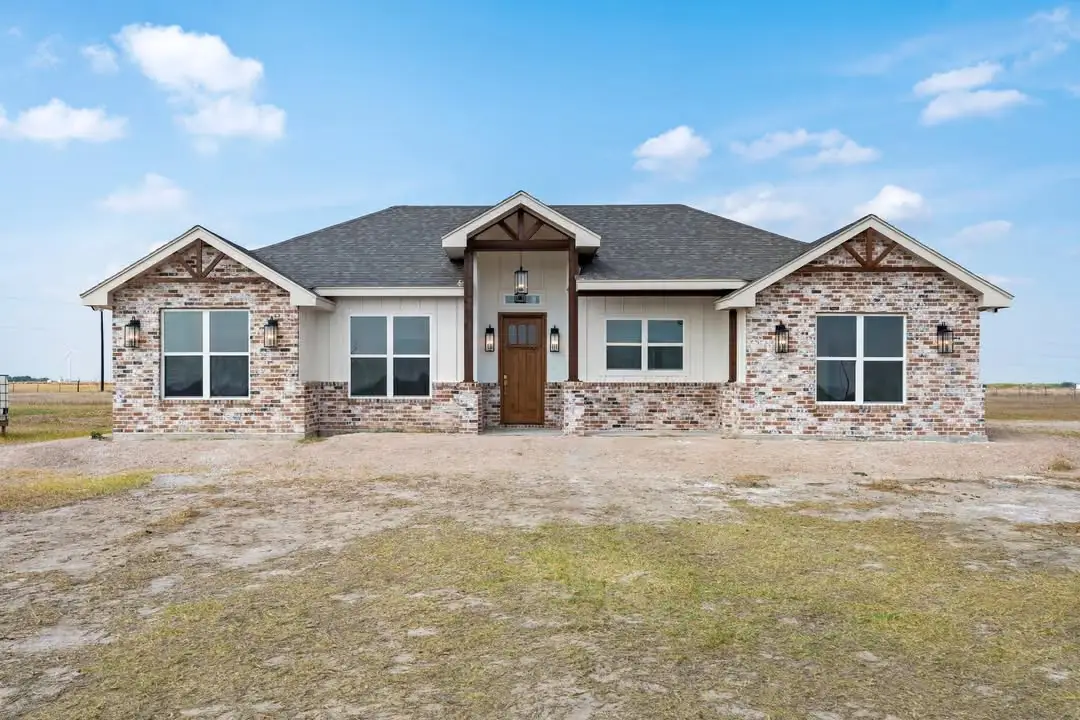
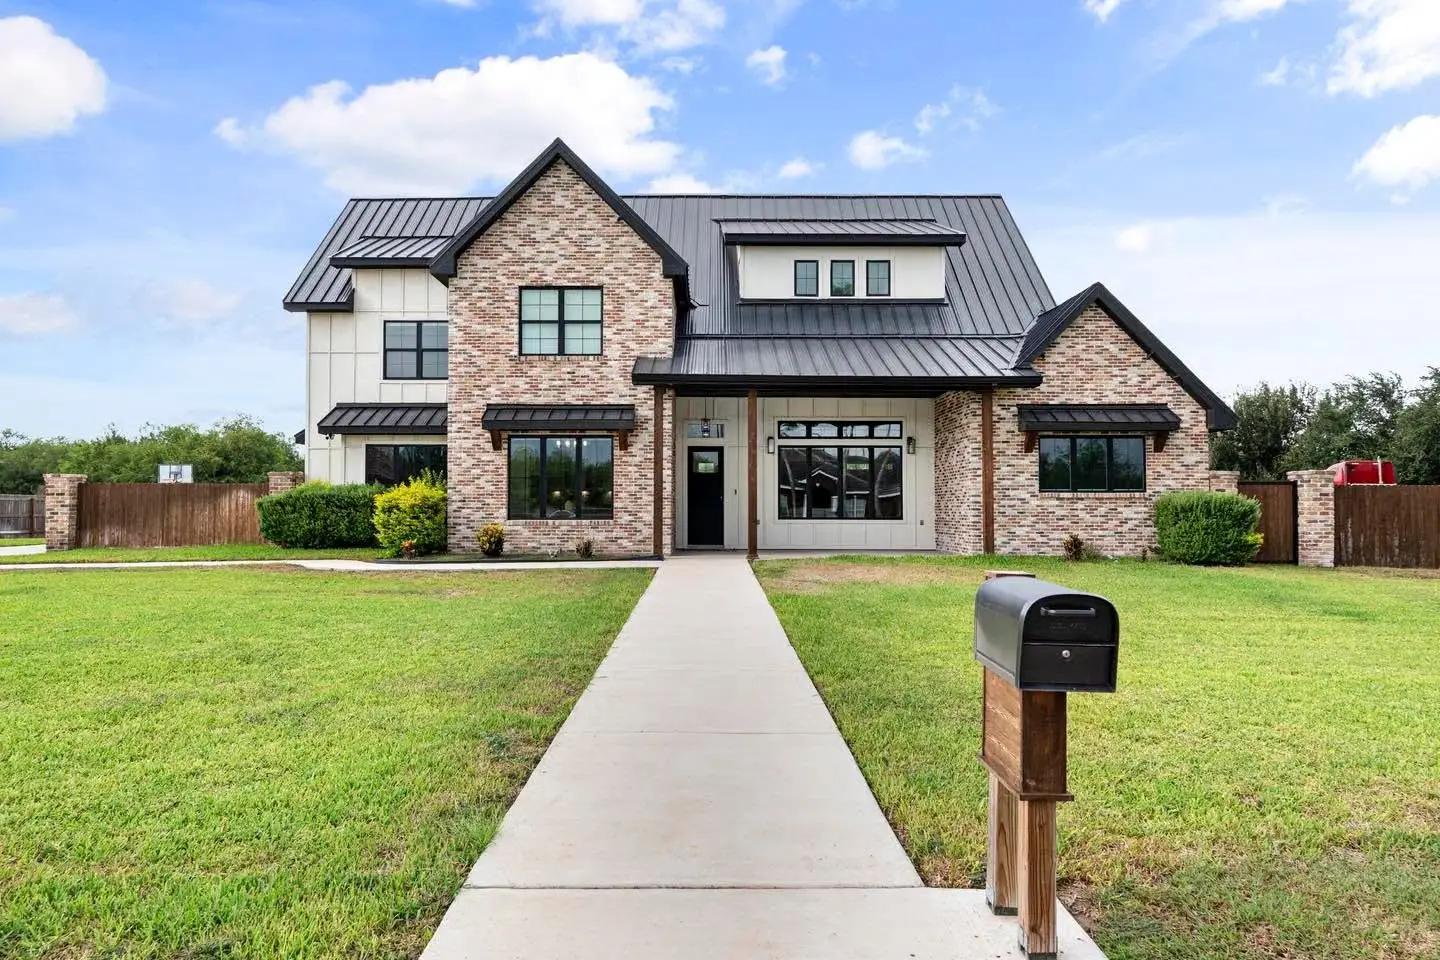
Permits, prices and site conditions change from county to county. Start with yours, or go straight to your city.
The Fully Loaded standard here runs $115 to $120 / sq ft, and financing guidance works the same way it does everywhere we build. Every city below has its own page with local permitting, pricing and site conditions.
The Fully Loaded standard here runs $120 to $130 / sq ft, and financing guidance works the same way it does everywhere we build. Every city below has its own page with local permitting, pricing and site conditions.
The Fully Loaded standard here runs $115 to $120 / sq ft, and financing guidance works the same way it does everywhere we build. Every city below has its own page with local permitting, pricing and site conditions.
The Fully Loaded standard here runs $130 to $145 / sq ft, and financing guidance works the same way it does everywhere we build. Every city below has its own page with local permitting, pricing and site conditions.
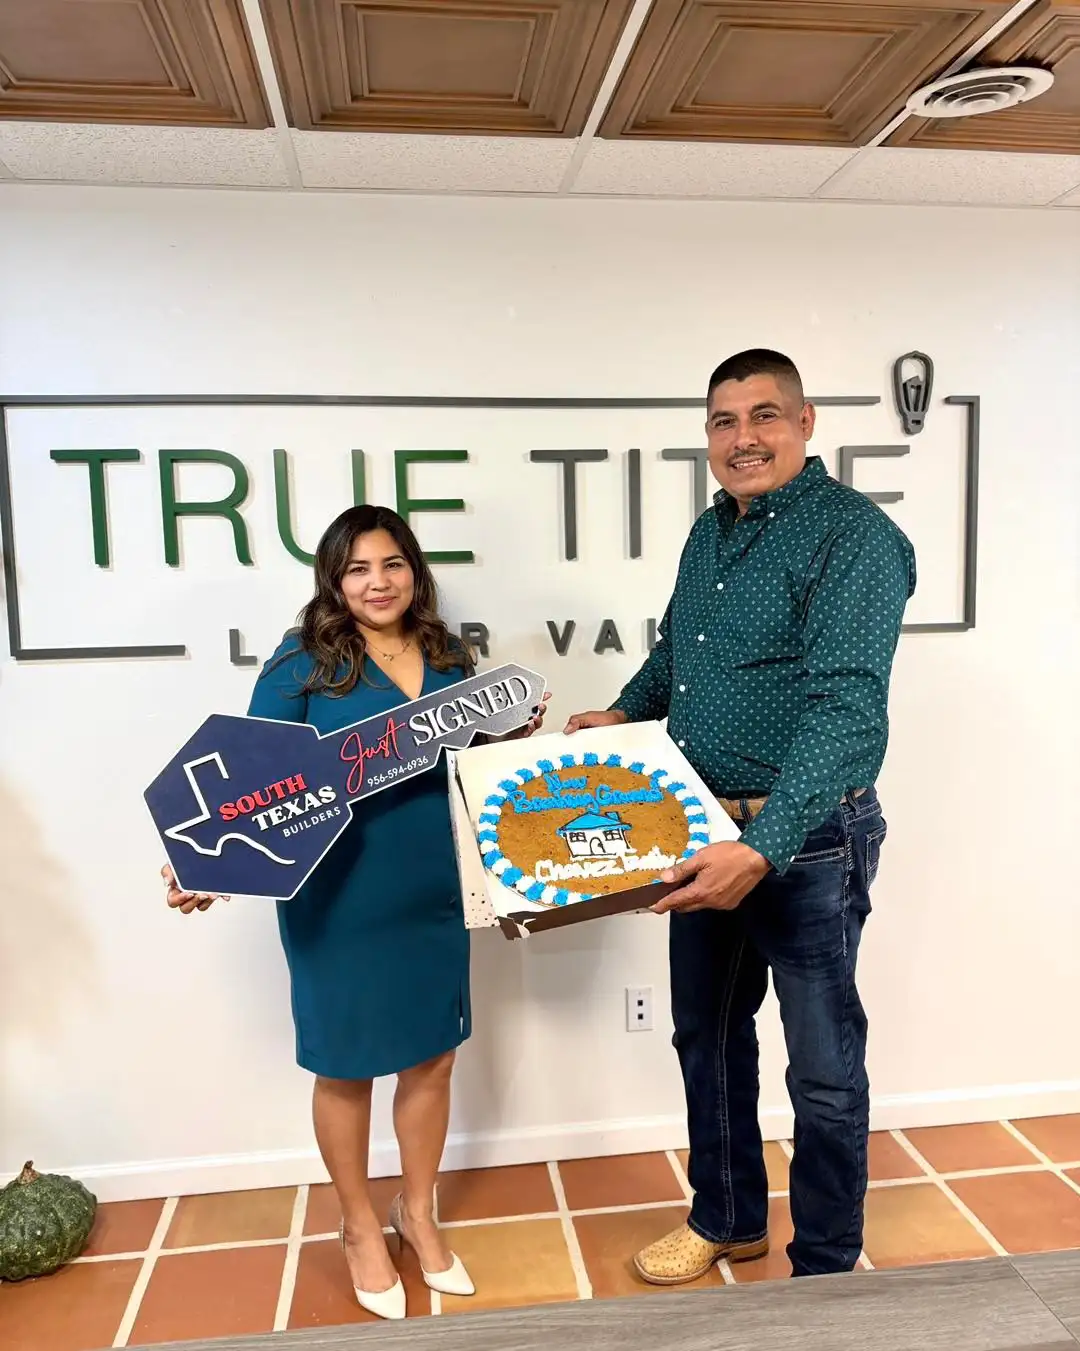
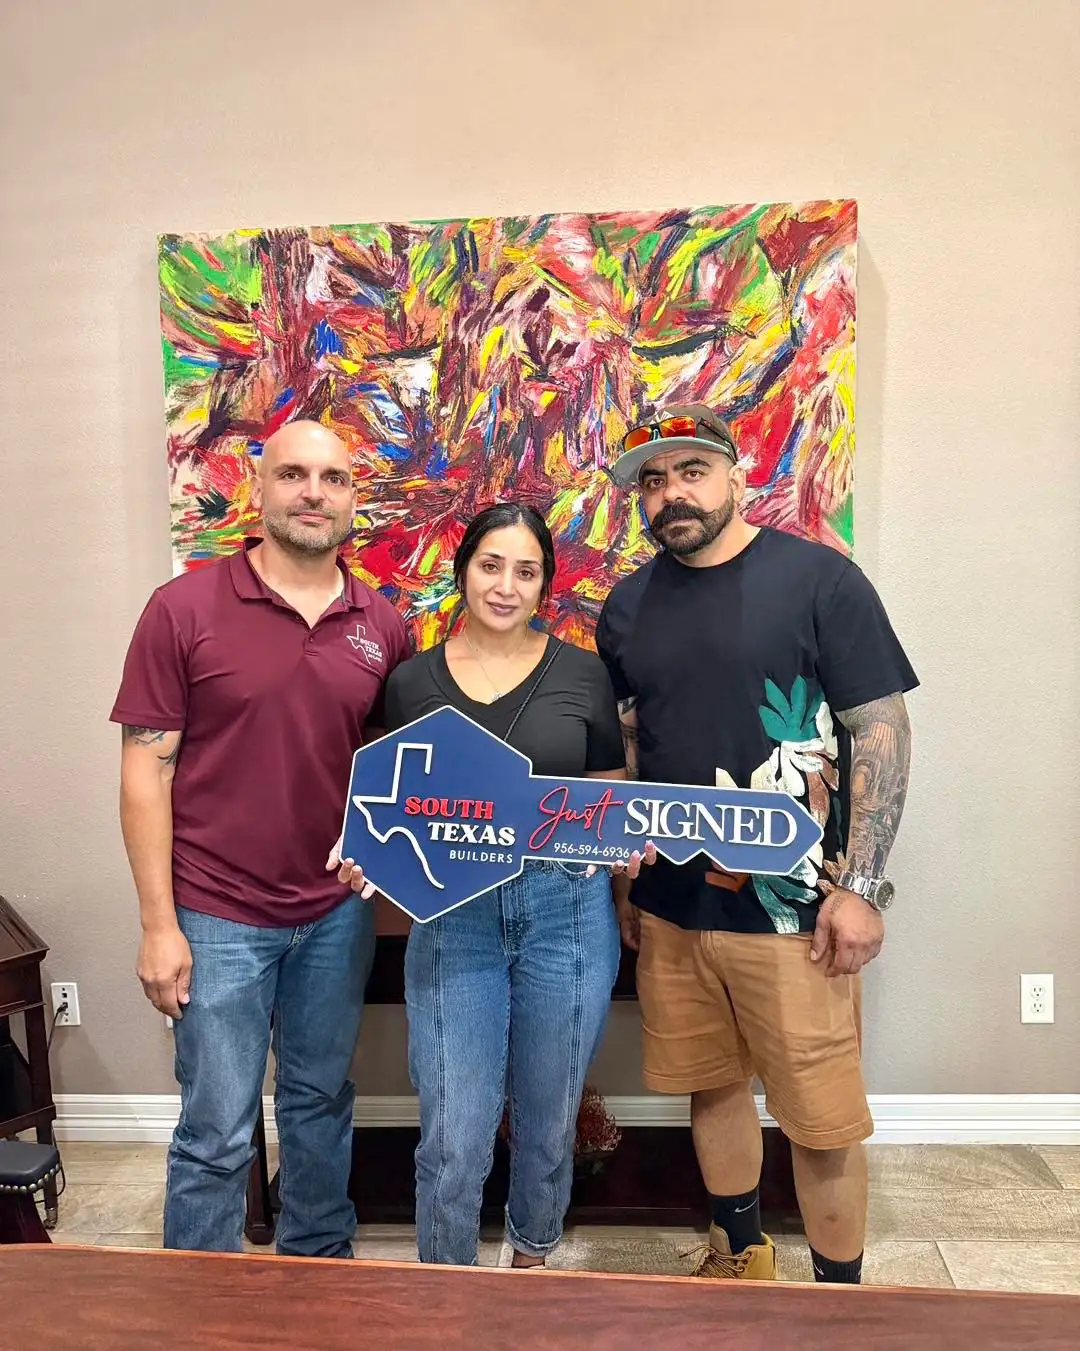
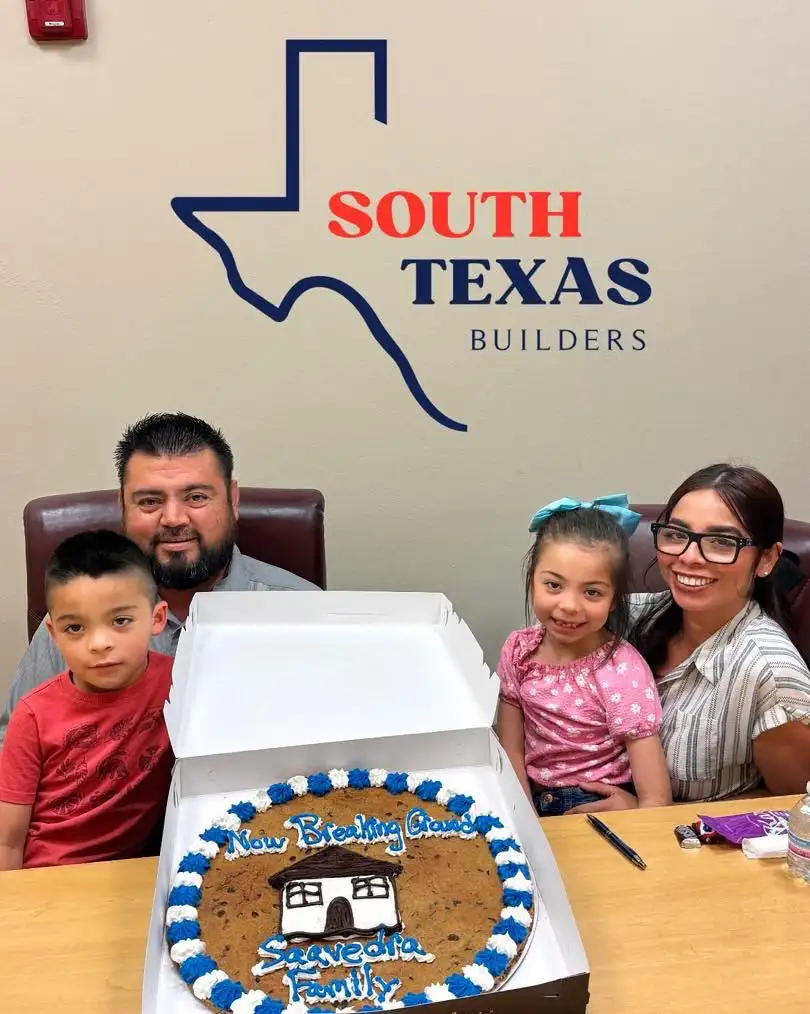
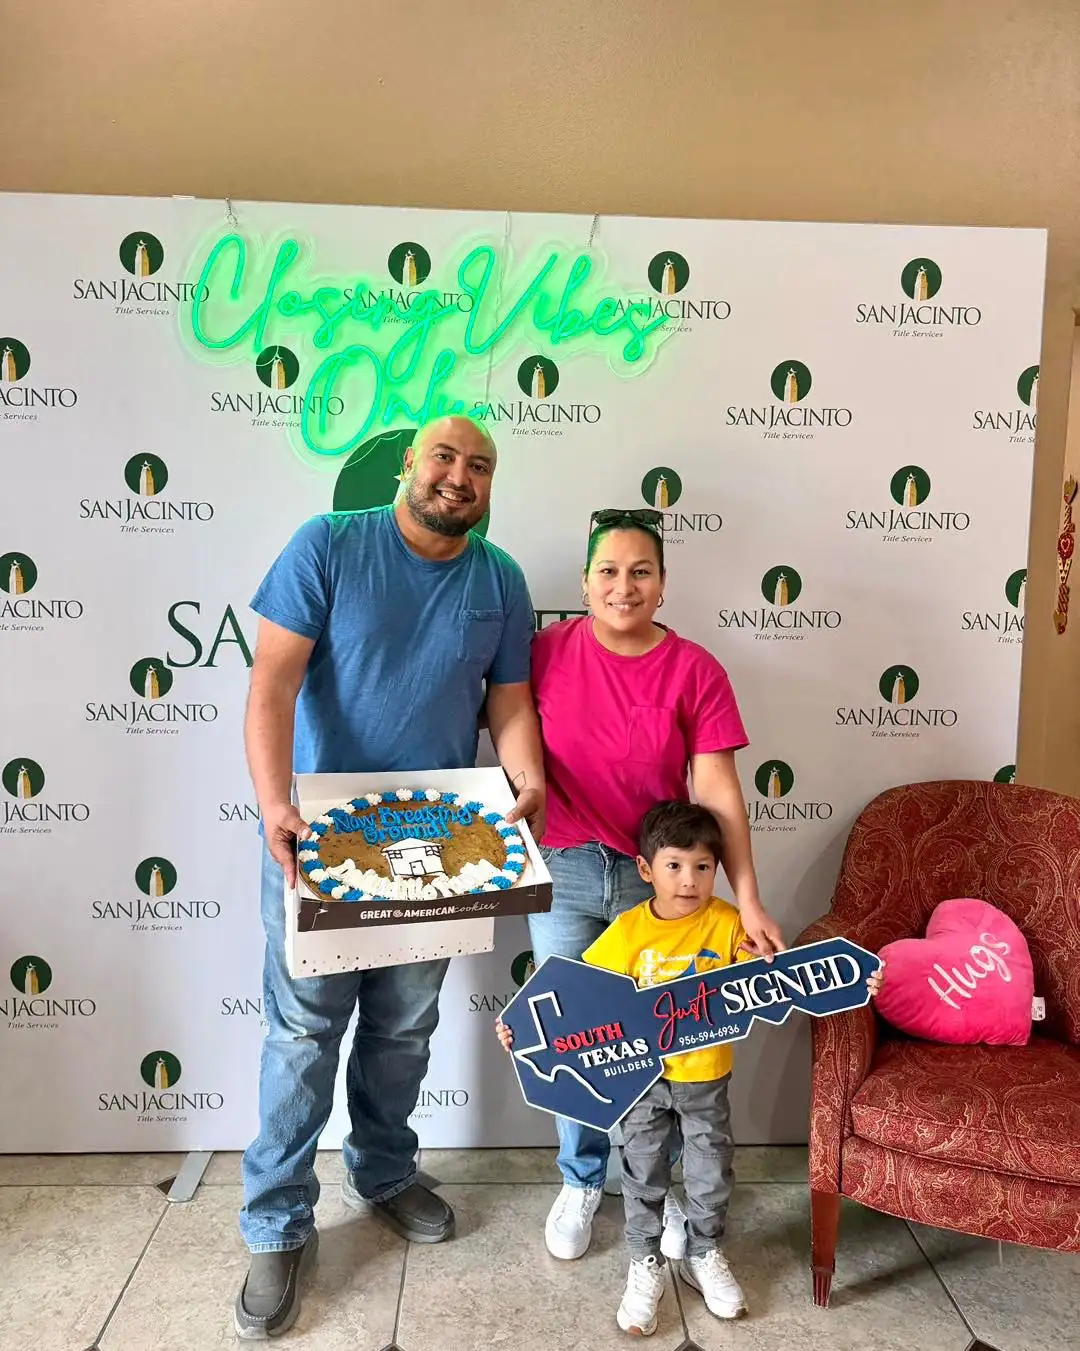
Photographed the day they signed, and quoted in their own words.
Read and watch all client stories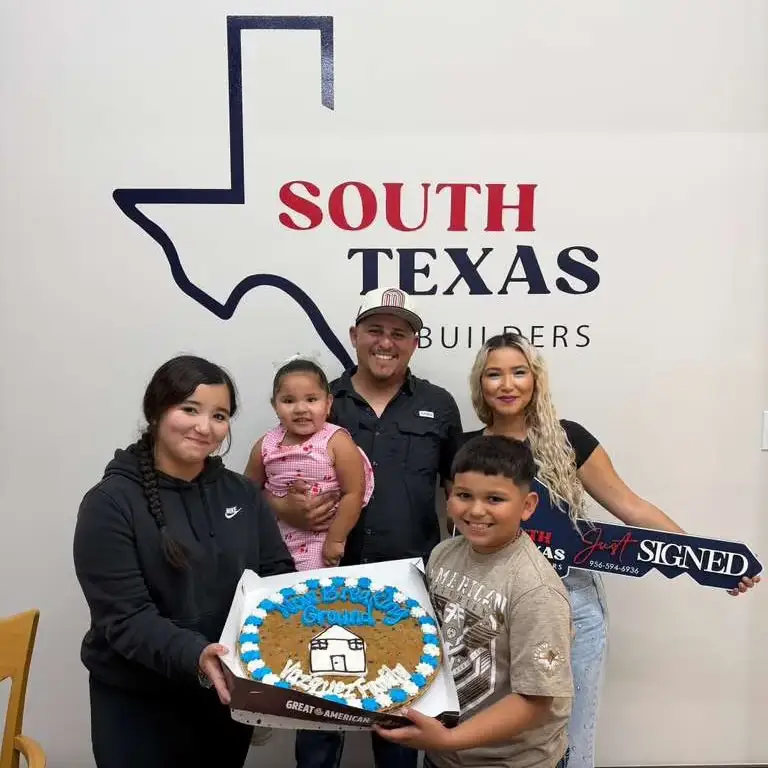
We’re the Vasquez family. We have been trying to build our home for three to four years. I just wanna say thank you to South Texas Builders and their team for making this dream come true.
Thank you South Texas family for making our dream come true.
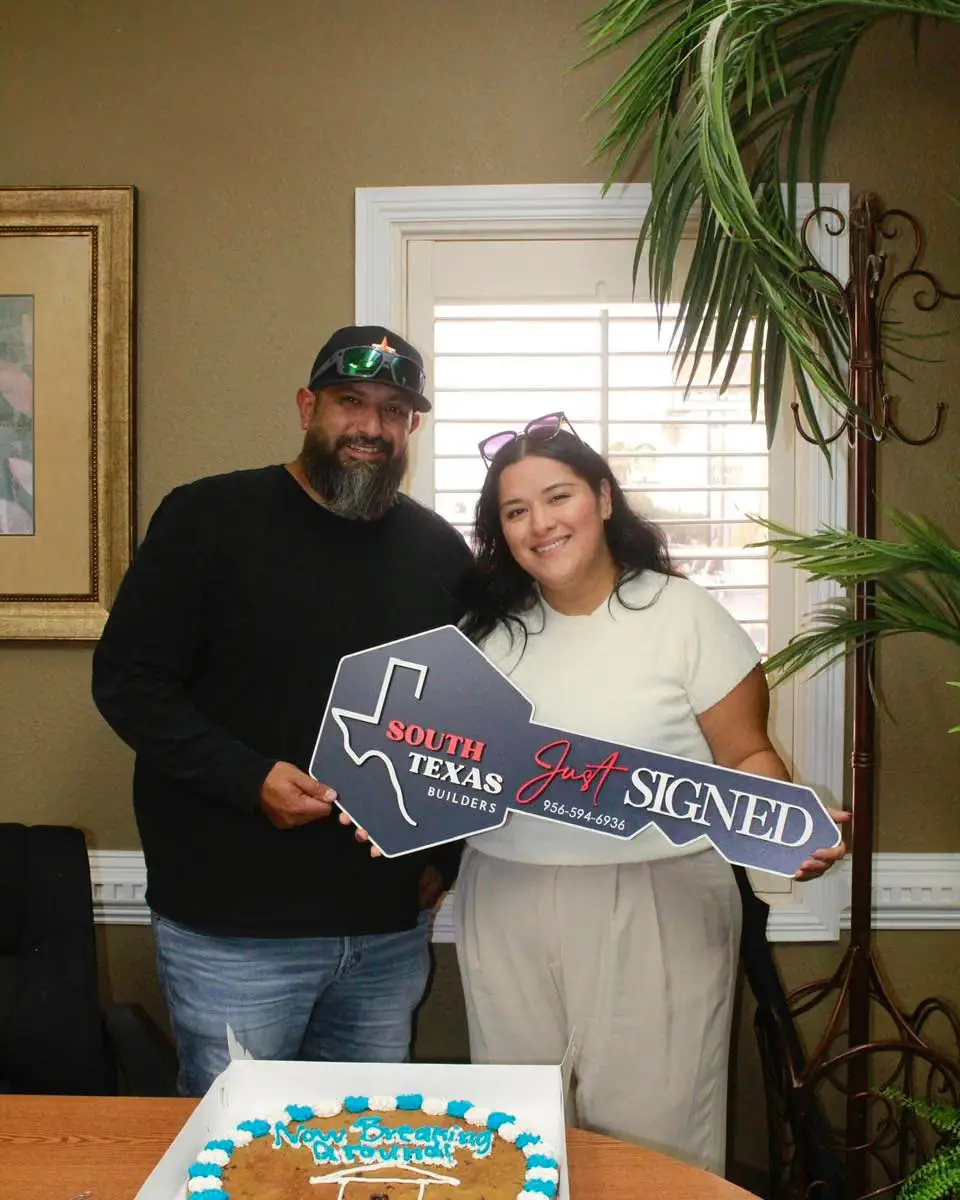
We want to thank South Texas Builders for building our dream home.
From the very beginning, from signing the contract, designing the blueprints, and choosing every detail, their team guided us through the entire process.
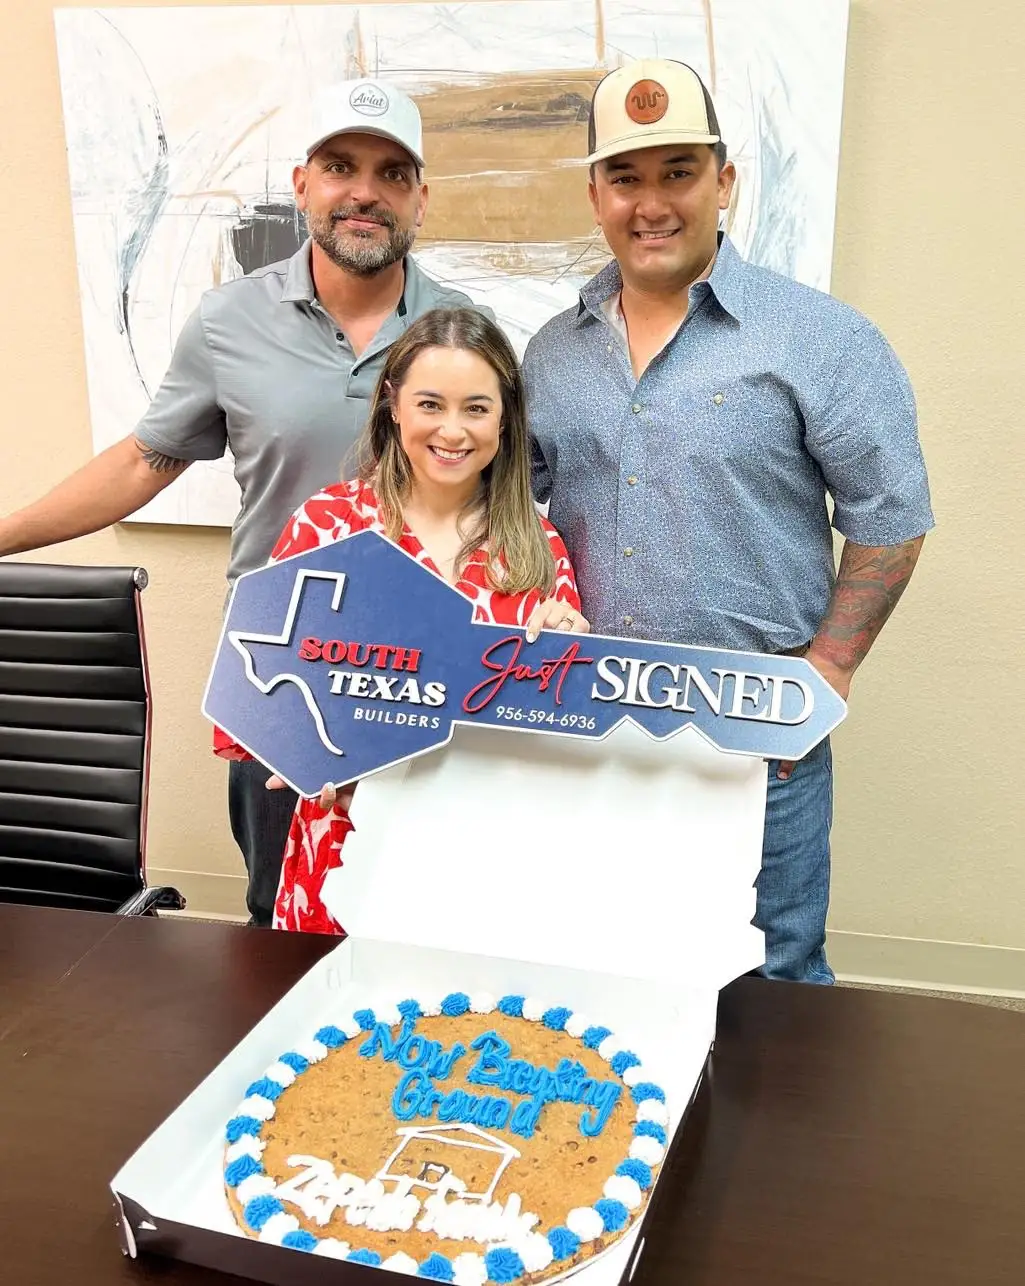
We want to thank South Texas Builders for building our home.
They evaluated our lot for free, explained every step, and designed a floor plan that fit perfectly on our property.
We can honestly say this was the best decision we’ve made for our family.
South Texas Builders made the process of building our first home much less intimidating than we expected.
We came in not knowing much about construction loans and they connected us with a lender the same day.
We are so grateful for this team.
Nosotros construimos nuestra casa en Mission con South Texas Builders y fue la mejor experiencia que pudimos haber tenido.
Llevábamos años ahorrando y cuando finalmente llegó el momento, queríamos hacer las cosas bien. El equipo nos explicó cada detalle del proceso, los permisos, los planos, las selecciones de materiales.
We built our home in Mission with South Texas Builders and it was the best experience we could have had.
We had been saving for years, and when the moment finally came we wanted to do it right. The team explained every detail of the process to us, the permits, the plans, the material selections.
Building with South Texas Builders was one of the best decisions we’ve ever made.
They knew exactly what the lender needed and kept us informed at every stage.
We are the González family and we built our home with South Texas Builders after a friend recommended them.
What stood out from day one was the honesty, they told us exactly what was included in the contract, what was not, and what everything would cost. No surprises.
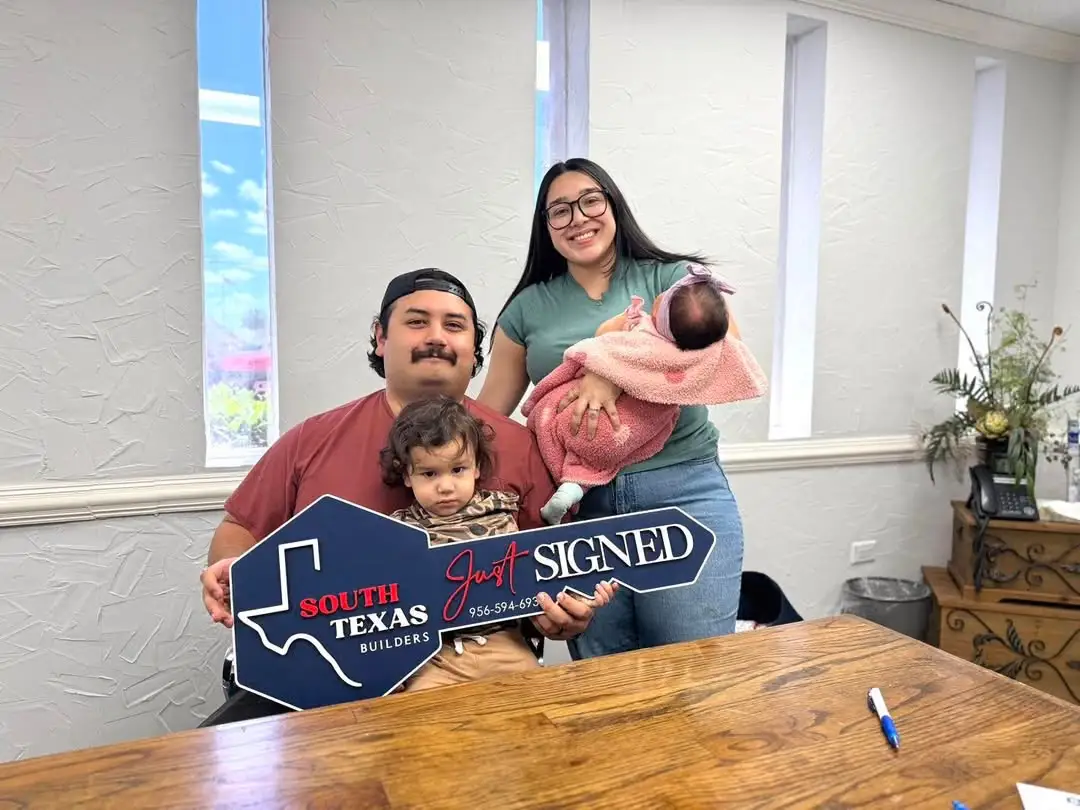
Thank you to South Texas Builders for turning what felt like an overwhelming process into one of the most exciting experiences of our lives.
The blueprint design process with the team was creative and fun, they really listened to what we wanted.
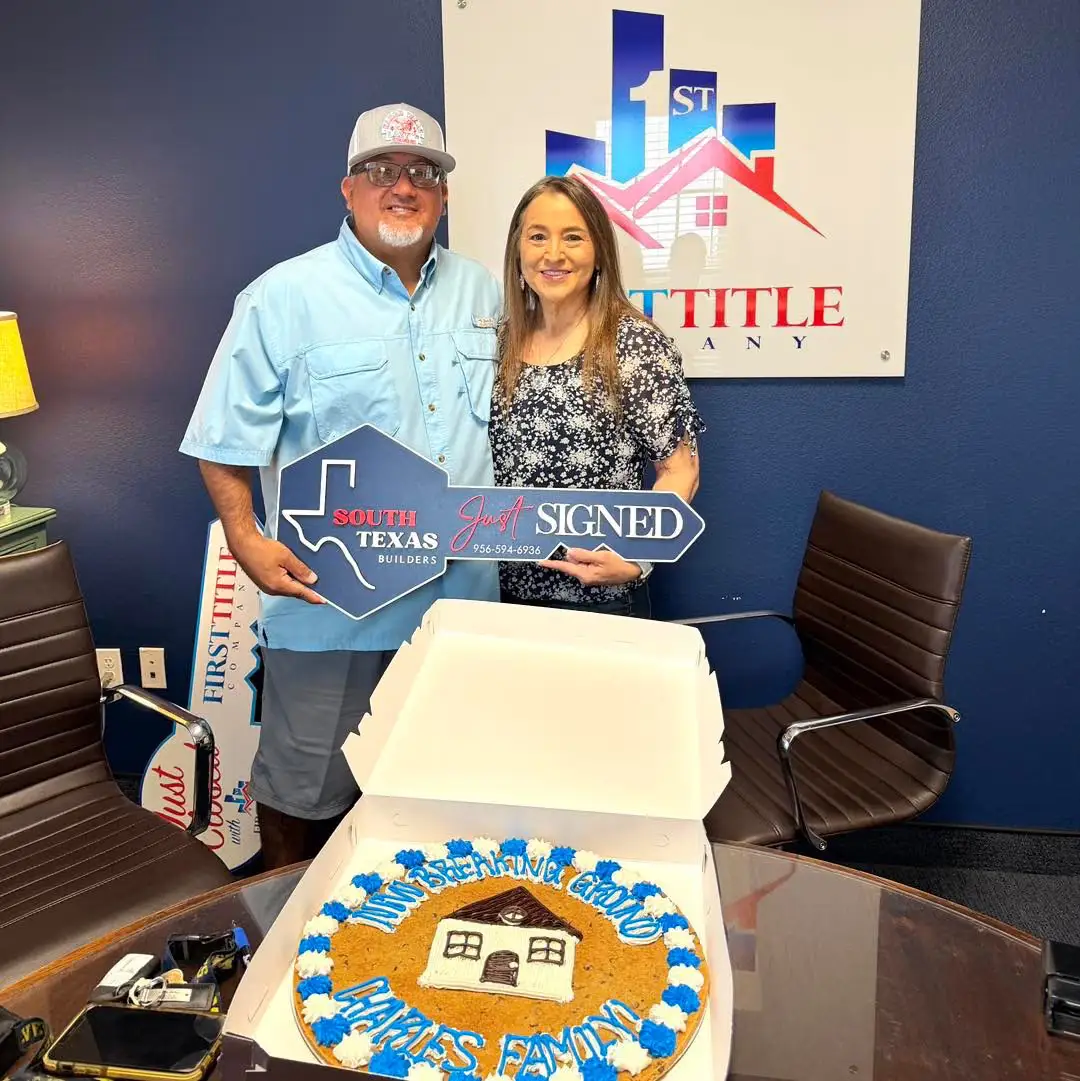
We moved to the Rio Grande Valley from out of state and knew we wanted to build rather than buy.
South Texas Builders was recommended to us and from our very first call they were professional, knowledgeable, and patient with all of our questions.
The answers people ask for before they book a call.
Yes. FHA is one of the most common paths for first time builders here because it needs only 3.5% down and has more flexible credit requirements than conventional financing.
For a new build you would typically use an FHA construction to permanent loan, a one time close that funds construction and converts to a standard FHA mortgage at completion, so you avoid a second closing. FHA generally looks for a 580 credit score at 3.5% down, or 500 to 579 with 10% down, and the home must meet FHA property standards. We will connect you with a local FHA lender who does construction regularly.
All the major construction financing programs available in Texas. FHA: 3.5% down, flexible credit. VA: zero down for eligible veterans, active duty service members and surviving spouses. Conventional: typically 10 to 20% down, often the best long term rate. One time close construction loans: cover the build and the permanent mortgage in a single loan. USDA Rural Development: zero down in eligible rural areas.
Which one fits depends on your credit, your down payment and where your lot sits. We will help you narrow it before you meet a lender.
Yes, and for those who qualify it is usually the strongest option: zero down payment, no private mortgage insurance, competitive rates, and the ability to finance construction and the permanent mortgage in a single one time close.
You will need your Certificate of Eligibility, the home must be your primary residence, and it must meet VA minimum property requirements. Not every lender offers VA construction financing, so the introduction matters, we work with local lenders who handle VA new construction routinely.
A construction loan funds the build in stages called draws, released as milestones are completed and inspected. You qualify based on credit, income and the appraised value of the finished home; you close once blueprints and selections are final; the lender then releases funds directly to the builder at each milestone.
During construction you typically pay interest only on the funds drawn so far, which keeps payments low while the house goes up. With a one time close, the loan converts automatically to a permanent mortgage at completion. With a two time close, you refinance at the end.
It depends on the program. FHA: 580 or above for 3.5% down, 500 to 579 with 10% down. VA: no official minimum, though most lenders want 580 to 620. Conventional: 620 minimum, with the best rates at 740 and above. USDA: typically 640. Construction loans: usually 620 to 680 depending on the lender.
If you are below those numbers today, that is a timeline question rather than a closed door. Paying down card balances, disputing errors and avoiding new debt can move a score meaningfully in three to twelve months, and the lenders we work with will tell you specifically what to fix first.
We do not originate loans, but we make the introduction and prepare you for it. We will point you to the right lender for your program, explain which documents to bring, and tell you what to expect from the conversation.
Pre approval usually takes one to three business days with a local lender and costs nothing. It is the single most useful first step, because it replaces a guess about your budget with a number we can design against.
It depends on the loan program. FHA construction loans need a minimum 3.5% down, about $8,750 on a $250,000 build. Conventional construction loans typically want 10 to 20%, so $25,000 to $50,000 on the same build. VA loans require no down payment for qualifying veterans and active duty service members. USDA loans require no down payment in eligible rural areas.
Beyond the down payment, plan for three to six months of reserves and closing costs of roughly 2 to 5% of the loan amount. We can introduce you to Valley lenders who close construction loans regularly and can prequalify you in a few days.
Next step
The first conversation is free and carries no obligation. Tell us where you are and we will tell you honestly what the next step should be.
Prefer to talk to a person?(956) 594-6936